Among the 44 company sample, median revenue was $11B, median market capitalization was $23B and median 12 month Total Shareholder Return (TSR) was 27% at the end of February 2014.
What We Found
The early findings and trends from these filers generally showed a continuation of trends from the 2013 proxy season. Early in 2014 companies:
- Received high levels of shareholder Say on Pay support
- Awarded CEO bonuses that were slightly higher as a percent of target compared to prior year earned bonuses, and
- Shifted more of the long-term incentive “LTI” program to performance based vehicles and decreased the emphasis on stock options
Say On Pay (SOP) Vote Results
In 2014, all Early Filers that released SOP results to-date (n=38) received majority shareholder support and 87% of companies received greater than 90% support. Among these companies there has been a steady uptick in the level of support at the 25th percentile over the last four years.
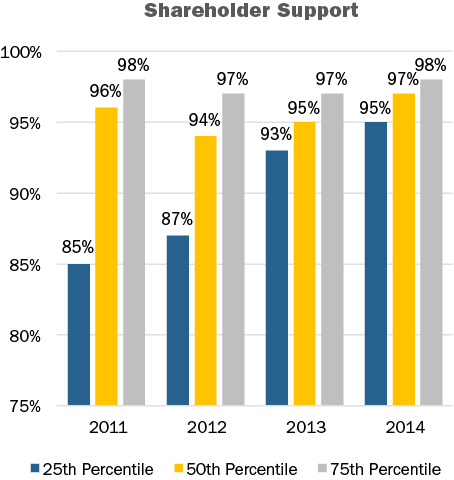
CAP Comment: SOP levels in early 2014 to-date continue to be strong. We expect similar SOP support levels for calendar year-end companies as we approach the 2014 annual meeting dates.
CHANGES IN SHORT AND LONG-TERM COMPENSATION
Base Salary
Among Early Filers, 46% of companies disclosed an increase to the CEO’s base salary in 2013 and the overall average base salary increase was 2.7%.2 CEOs in the Industrials industry received the largest average base salary increase (8.7%) followed by Consumer Staples (3.9%).
CAP Comment: The average executive base salary increase among the Early Filers is consistent with projected merit increases in the broader market where we are generally seeing 3.0% increases for 2014.
Short-term Incentive Payouts
Bonus payouts as a percent of target for the Early Filers increased slightly at the median. The median CEO bonus payout for 2013 was 100% of target compared to 97% in 2012. In general, there was a slight shift upwards in the bonus payouts when compared to the prior year. This is in-line with overall expectations as companies’ earnings and income also had modest growth year-over-year.
|
|
Annual Incentive Payout as a % of Target |
|
|
Summary Statistics |
2012 |
2013 |
|
75th Percentile |
118% |
119% |
|
50th Percentile |
97% |
100% |
|
25th Percentile |
74% |
84% |
51% of Early Filers paid above target in 2013, compared to 46% in 2012. Of the companies that paid above target, median year-over-year increases in revenue, earnings and income growth were in the 10-20% range, compared to 5% for all Early Filers companies.
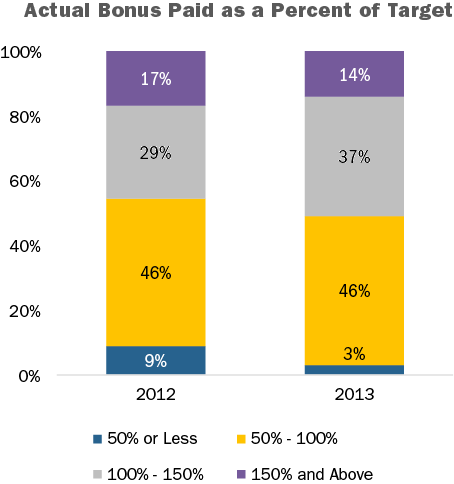
CAP Comment: Year-over-year financial performance results are aligned with CEO bonus payouts for the Early Filers. Companies are putting more time and effort into the goal setting process to ensure an appropriate pay and performance alignment; investors and proxy advisory firms increasingly focus on the performance goals and rigor of the incentive plan targets.
Long-term Incentive Mix
Over the last two years, the portion of the LTI mix delivered in a performance-based vehicle has increased in the general market. Early Filers showed a continuing, consistent shift, placing more emphasis on performance-based LTI and less emphasis on stock options; the weighting on time based restricted stock remained flat.
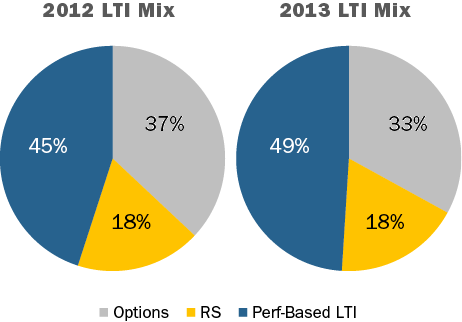
Approximately 85% of the Early Filers use two or three vehicles to deliver their long-term incentives.
CAP Comment: A general trend over the last couple of years has been a de-emphasis on stock options as part of the LTI program and an increase on the portion of performance based LTI. ISS is supporting this shift as they do not consider options to be performance-based.
Disclosed changes to compensation programs and polices
Companies continue to modify their compensation programs as they reassess program features in light of business/strategic changes and/or evolving shareholder and proxy advisory groups’ hot buttons. 36 of the 44 companies (82%) we researched disclosed making a change to their compensation programs or policies. The most prevalent change among the Early Filers was a modification to the company’s benchmarking peer group. Peer group changes are typically a result of companies trying to better align the peer group median size with that of their own company.
|
|
2013 |
% of Cos. |
|
Type of Change Reported in CD&A |
No. of Cos. |
n=44 |
|
Modified peer group |
22 |
50% |
|
Decreased weighting of options in LTI mix |
10 |
23% |
|
Increased weighting on perf.-based LTI |
9 |
20% |
|
Adopted / expanded clawback policy |
6 |
14% |
|
Adopted hedging and/or pledging |
5 |
11% |
Note: Percentages add up to greater than 100% due to multiple responses
CAP Comment: Modifications to a company’s peer group is common as Compensation Committees and management review appropriate peers for benchmarking on an annual or biennial basis. Given that ISS and Glass Lewis consider a company’s peer group when conducting their analyses, it is another reason that assessing the appropriateness of peer companies is a valuable exercise.
Similar to last year, companies continue to modify their clawback policy as a sign of good corporate governance. Companies are not universally waiting for final Dodd-Frank regulations before making adjustments to their policy. The uptick in the disclosure of hedging/pledging policies also continued, and overall, 86% of Early Filers disclose having both. Lastly, 14% of Early Filers voluntarily disclosed a supplemental table, graph or discussion of realized/realizable pay. In-line with CAP’s recent research on this topic and disclosure in 2013 proxies, these companies tend to compare realized/realizable pay with target or Summary Compensation Table pay values, as well as alignment with TSR.
Conclusions
While the Early Filers research is a sneak preview into the upcoming proxy season, we expect to see directionally consistent trends with these changes and practices indicated from our research. Companies are continuing to demonstrate good corporate governance and policies / programs that enhance company performance and pay linkages. Since there have not been significant changes in proxy advisory firm policies or expanded Dodd- Frank legislation, we do not expect to see significant program overhaul in the current proxy season. Companies with low SOP support will likely disclose more significant program modification.
1 Calendar year-end companies were not included in the analysis.
2 Based on companies whose current CEO has held the position for two years.
To address the limitations of SCT and GPBA data, companies have begun to disclose realized and realizable pay (see table below for definitions of realized and realizable pay). In order to evaluate this growing trend, Compensation Advisory Partners (“CAP”) reviewed the 2013 proxy statements of public Fortune 500 companies and tallied the disclosure of realized and realizable pay. For companies that presented a discussion on this topic, we recorded the use of graphics (e.g., tables and charts), we considered what methods companies used to compare different definitions of pay (e.g., vs. SCT/target pay, relative to a peer group, etc.), and we also tracked companies that supplemented their disclosure with the use of performance metrics.
|
Pay Component |
Realized |
Realizable |
|
Time Period |
1 – 5 years |
|
|
Base Salary |
Base salary disclosed in Summary Compensation Table (“SCT”) |
|
|
Bonus |
Actual bonuses/non-equity incentive (annual variable cash incentive) disclosed in the SCT |
|
|
Time-based Equity Awards |
||
|
Stock Options |
Value gained upon exercise for all stock options exercised within measurement period |
Valued at end of performance/measurement period Two alternative approaches: Intrinsic (in-the-money) value of awards granted during measurement period Updated Black-Scholes valuation of awards granted within measurement period |
|
Restricted Stock/Units |
Value at vest for all shares/units that vest within measurement period |
Value at end of measurement period, of all shares/units granted during measured period |
|
Performance-Contingent Equity Awards |
||
|
Stock/Stock Units |
Value upon payout, for all awards that paid during measured period |
Two alternative approaches: Value upon payout, for all awards that paid during measured period Awards granted, vested, and paid out during measured period; if unvested, target value of shares awarded during measured period |
|
Long-term Cash |
Long-term cash incentive payouts during measurement period disclosed in SCT |
Two alternative approaches: Long-term cash incentive payouts during measurement period disclosed in SCT Awards granted, vested, and paid out during measured period; if unvested, target value of long-term cash awarded during measurement period |
Results
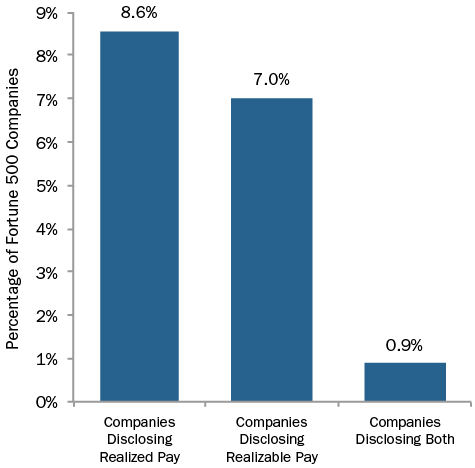
Among our sample of Fortune 500 companies, 15% supplemented the SCT and GPBA with realized and/or realizable pay disclosure. Approximately 9% of our sample disclosed realized pay, 7% disclosed realizable pay, and 1% disclosed both.
Realized Pay Disclosure
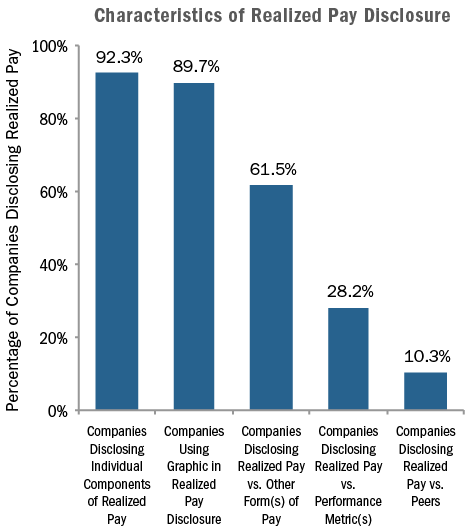
For companies disclosing realized pay, the most common methodology used was base salary actually paid, bonus actually paid, the value of restricted stock that vested during the period, and the value realized upon exercise of options during the period. In a lesser number of cases, companies also included all other compensation and the change in pension value. The majority of companies presented realized pay on an absolute basis (i.e., on an individual company basis, not against peers or some other index). CAP found that of the companies disclosing/discussing the concept of realized pay, most (90%) used some type of chart or table to discuss the concept, 62% compared their realized pay to some other definition of compensation (companies were equally divided between disclosing a comparison of realized pay to SCT pay or to the executive’s target compensation), and approximately 28% of companies compare a performance metric (most commonly TSR) to a graphic depiction of realized pay.
Companies disclosing realized pay had a median cumulative TSR of 7% and 5% on a 1- and 3-year basis, respectively—placing the majority of disclosing companies well below the median of the Fortune 500.
|
|
Cumulative TSR at 12/31/2012 |
|
|
Fortune 500 |
1-year |
3-year |
|
Median |
14.1% |
35.5% |
|
25th Percentile |
1.6% |
2.4% |
|
15th Percentile |
-3.9% |
-6.4% |
|
10th Percentile |
-10.8% |
-18.7% |
|
Companies Disclosing Realized Pay |
|
|
|
75th Percentile |
24.7% |
38.6% |
|
Median |
6.5% |
5.2% |
|
25th Percentile |
-7.8% |
-10.7% |
Realizable Pay Disclosure
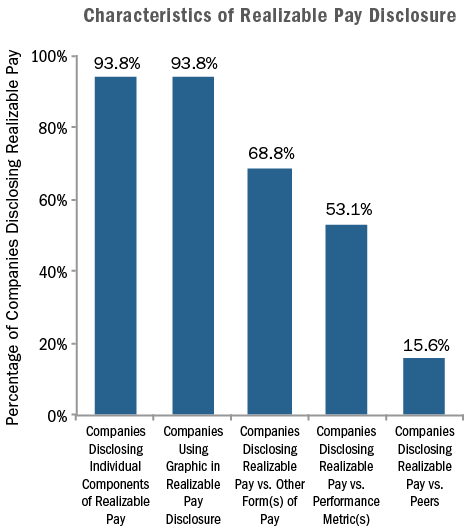
As stated above, among companies that disclosed a supplemental definition of pay, approximately half used some form of realizable pay. Typically, realizable pay is calculated as base salary, actual bonus paid, and long-term incentives granted and valued at the end of the period. For restricted stock, the value is calculated by multiplying the number of shares granted by the stock price at the end of the period. For stock options, the value is most often calculated as the intrinsic (in-the-money) value based on the stock price at the end of the period (Black-Scholes option values are also used, albeit less frequently). For performance shares, the calculation is generally based on the payout for shares granted within the period or the target number of shares granted for awards that have not vested, valued at the end of the period. Most of the companies disclosing used an accompanying table or graph to demonstrate the concept and the most commonly used graphics were: tables or charts showing the side-by-side difference between grant date/target pay vs. realizable pay, realizable pay vs. total shareholder return (TSR), or some combination of the two. Approximately 90% of companies disclosing realizable pay had SCT/GPBA pay data that was greater than realizable pay.
Like realized pay companies, a majority of Fortune 500 companies disclosing realizable pay had 1- and 3-year TSR at 12/31/2012 that trailed the median of the full Fortune 500 group. More specifically, the median TSR of realizable pay companies was slightly above the 25th percentile of the Fortune 500 on a 1-year basis, and between the 15th percentile and 25th percentile on a 3-year basis.
|
|
Cumulative TSR at 12/31/2012 |
|
|
Fortune 500 |
1-year |
3-year |
|
Median |
14.1% |
35.5% |
|
25th Percentile |
1.6% |
2.4% |
|
15th Percentile |
-3.9% |
-6.4% |
|
10th Percentile |
-10.8% |
-18.7% |
|
Companies Disclosing Realizable Pay |
|
|
|
75th Percentile |
19.2% |
37.1% |
|
Median |
1.7% |
-1.8% |
|
25th Percentile |
-15.0% |
-30.0% |
Conclusion
The 2013 proxy season was the first year where we saw a meaningful number of companies disclosing realized and/or realizable pay and with the 2014 proxy season fast approaching, we fully expect to see an increase in supplementary pay disclosure, particularly for those companies with below-average TSR.
Research assistance provided by: Kyle Eastman, Michael Biagi, Ryan Colucci.
Note: For detailed findings or specific company examples, please call or email Eric Hosken at Compensation Advisory Partners. We expect to publish a more comprehensive discussion of the topic in the Q2 2014 World at Work Journal.
Email: [email protected]
Phone: (212) 921-9363
CHANGES IN ANNUAL INCENTIVE PLAN DESIGN
Overall, 37% of companies made changes to their annual incentive plan design in 2012 or 2013. The most common changes were to increase the target incentive opportunity for the CEO and/or CFO (43% of companies making a change to increase target award opportunities) or to change to the annual incentive performance metrics (35%). Companies continue to review and enhance the pay-for-performance relationship through changes to the annual incentive program.
|
Type of Change Reported in CD&A |
2012 No. of Cos. |
% of Cos. Reporting Changes |
|
|
2012 (n = 37) |
2011 (n = 43) |
||
|
Increase target award opportunities (CEO and/or CFO) |
16 |
43% |
28% |
|
Change in performance metrics used to fund awards |
13 |
35% |
42% |
|
Change in performance metric weighting/mix |
4 |
11% |
21% |
|
Adopt mandatory deferral mechanism |
4 |
11% |
n/a |
|
Change in maximum award payout |
3 |
8% |
12% |
|
Other Changes |
8 |
22% |
19% |
Note: Due to multiple responses, does not add up to 100%.
Change in Target Bonus Opportunity
Last year median target bonus opportunities for the CEO and CFO positions increased by 6 and 1 percentage points to 159% and 101% of salary, respectively. The target bonus opportunity for CEOs in the Technology industry increased by 50 percentage points in 2012 due to an increase in the target opportunity at Apple (from 50% to 100% of salary) and Verizon (from 187.5% to 250%). Conversely, in the Consumer Goods industry, target bonus opportunities decreased year over year due to new incumbents in these roles.
|
Industry |
Median Target Bonus as a % of Salary |
|||||
|
CEO |
CFO |
|||||
|
2012 |
2011 |
Change in %age Pts. |
2012 |
2011 |
Change in %age Pts. |
|
|
Automotive |
138% |
130% |
+8% |
88% |
88% |
0% |
|
Consumer Goods |
160% |
170% |
-10% |
90% |
100% |
-10% |
|
Financial Services |
n/m |
n/m |
n/m |
n/m |
n/m |
n/m |
|
Health Care |
145% |
145% |
0% |
101% |
100% |
+1% |
|
Insurance |
200% |
200% |
0% |
130% |
120% |
+10% |
|
Manufacturing |
142% |
156% |
-14% |
93% |
95% |
-2% |
|
Pharmaceutical |
150% |
150% |
0% |
97% |
91% |
+6% |
|
Retail |
190% |
168% |
+12% |
90% |
85% |
+5% |
|
Technology |
250% |
200% |
+50% |
135% |
121% |
+14% |
|
Total Sample |
159% |
153% |
+6% |
101% |
100% |
+1% |
Note: Financial Services industry is excluded since most companies in our study do not disclose target bonus opportunities for the Named Executive Officers.
Change in Performance Metrics
Of the companies that changed or plan to change the performance metric:
- Nine (9) companies added metrics to the current plan
- Two (2) companies reduced the number of metrics, and
- Two (2) companies kept the same number of metrics but replaced a metric in the incentive plan.
Several companies indicated that their rationale for changing annual incentive metrics was, in large part, to better align executive pay with the business strategy and shareholder interests:
- Caterpillar: Incorporated Operating Profit After Capital Charge (OPACC) as a measure, to reflect how the Company is utilizing its assets in order to generate shareholder value
- CIGNA: Added a customer loyalty metric in 2013 to emphasize its business strategy and focus on the customers it serves
- Hewlett Packard: Introduced year over year improvement in Return on Invested Capital as an annual incentive metric to focus executives on the business turnaround
ANNUAL INCENTIVE PLAN DESIGN / PRACTICES
Award Leverage
Most companies reviewed did not disclose a threshold level of performance required to receive a bonus payment. Instead, these companies disclosed a minimum bonus of $0. For the 37 companies that did disclose a threshold bonus, 50% of target is the most prevalent payout percentage. However 20 companies, disclose a minimum bonus payout of less than 50% of target with a majority of these companies paying out for results based on one of multiple plan metrics. A majority of companies (58%) have a maximum bonus opportunity of 200% of target bonus. Thirteen (13) companies have a maximum bonus of 250% of target or higher. Four (4) of these companies are in the Consumer Goods industry and three (3) are in the Technology industry.
|
Threshold as a % of Target (n=37) |
||
|
Range |
# of Cos. |
% of Cos. |
|
< 25% |
10 |
27% |
|
25% < 50% |
10 |
27% |
|
50% |
12 |
32% |
|
50% < 75% |
1 |
3% |
|
75 <100% |
4 |
11% |
|
Maximum as a % of Target (n = 78) |
||
|
Range |
# of Cos. |
% of Cos. |
|
100% < 150% |
2 |
3% |
|
150% < 200% |
16 |
21% |
|
200% |
45 |
58% |
|
200% < 250% |
2 |
3% |
|
> 250% |
13 |
17% |
Of the six (6) companies that made changes to their maximum bonus potential in 2012/2013, three (3) companies increased the maximum bonus potential and three (3) companies reduced the maximum. Two (2) of these companies (Allstate and Colgate-Palmolive) changed the maximum payout for the CEO only.
Annual Incentive Plan Metrics
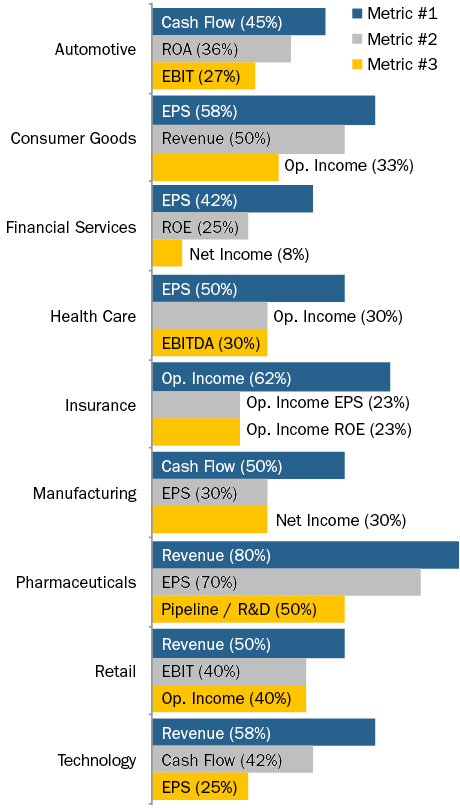
Similar to 2011, Revenue, EPS, Cash Flow and Operating Income continue to be the most prevalent metrics used across all companies, although we see some variation in metrics by industry. In 2013, 30% of companies disclose using two (2) metrics in their annual incentive programs, 29% use three (3) metrics, and 12% of companies use four (4) or more metrics. Approximately 85% of these companies use a profit-based metric in combination with Revenue and/or Cash Flow.
Refer to the chart below for the three (3) most prevalent metrics by industry:
|
Industry |
Actual Bonus as a % of Target Bonus – CEO |
|||||
|
2012 |
2011 |
|||||
|
25th%ile |
Median |
75th%ile |
25th%ile |
Median |
75th%ile |
|
|
Automotive |
69% |
102% |
131% |
130% |
153% |
186% |
|
Consumer Goods |
94% |
103% |
137% |
78% |
132% |
149% |
|
Financial Services |
44% |
80% |
120% |
111% |
114% |
130% |
|
Health Care |
103% |
127% |
157% |
116% |
127% |
159% |
|
Insurance |
112% |
130% |
144% |
85% |
106% |
130% |
|
Manufacturing |
100% |
107% |
146% |
119% |
136% |
162% |
|
Pharmaceutical |
125% |
142% |
156% |
130% |
144% |
161% |
|
Retail |
79% |
117% |
136% |
112% |
129% |
147% |
|
Technology |
90% |
99% |
124% |
75% |
100% |
149% |
|
Total Sample |
93% |
112% |
144% |
105% |
133% |
156% |
Note: Most companies in the Financial Services industry does not disclose target bonus. Figures for the Financial Services industry reflects actual bonus as a percentage of 3-year average actual bonus.
2012 Actual Bonus Payout
Similar to 2011, approximately 95% of companies awarded bonuses to their Named Executive Officers for 2012 performance. Overall, the median CEO bonus was 112% of target compared to 133% in 2011, indicating that 2012 performance generally exceeded par, but was not as strong as 2011 performance. Median 2012 bonus payouts in the Health Care, Insurance, Pharmaceutical and Retail industries exceeded target by 15 – 40 percentage points while payouts in the Automotive, Consumer Goods, Manufacturing and Technology industries were closer to target.
15% of companies in our study require executives to defer all or a portion of their annual incentive payout. Nearly 50% of companies that require a portion of the annual incentive award to be deferred are in the Financial Services industry. Among companies with mandatory deferrals outside of the Financial Services industry, two (2) companies pay a portion of the annual incentive in restricted stock units if the total payout exceeds a specific level:
- HCA Holdings: Any bonus payout above target is delivered 50% in cash and 50% in restricted stock units
- 3M: Annual incentive payouts in excess of 200% of target are paid in the form of restricted stock units
CONCLUSIONS
Companies are continuing to refine their annual incentive program to ensure executive pay is aligned with the Company’s business strategy and key success indicators. These recent trends also indicate that companies are modestly increasing CEO pay through the bonus opportunity and award leverage. Actual payouts for 2012, however, indicate stronger performance goals and moderately above target payouts, yet lower than the previous year. Revenue, EPS, Cash Flow and Operating Income continue to be the most prevalent annual incentive plan metrics with a majority of companies using two (30%) or three (29%) metrics to reward executives for company performance. We expect companies to continue to refine metrics and performance goals / leverage linkages in the annual incentive plan as shareholders and proxy advisory firms scrutinize the executive compensation program.
Among the 100 company sample, median revenue was $33B, median market capitalization was $37B and median Total Shareholder Return (TSR) was 19% in 2012.
What We Found
Although shareholder support for Say on Pay has been increasing year-over-year with a significant majority of companies receiving over 90% support, companies continue to regularly review and modify their executive compensation programs in response to shareholders, proxy advisory firms and good governance practices. Consistent with our findings last year, companies continue to modify clawback policies and scale back perquisites. New to our research in 2013, hedging /pledging polices have also gained traction as a result of Dodd-Frank and ISS’ policies.
Dodd Frank
The Dodd Frank Wall Street Reform and Consumer Protection Act (Dodd Frank) was signed into law in 2010 and will require the following governance practices:
- Companies must implement a clawback policy for executive officers that allows for recoupment of any incentive compensation, with a three-year look back, due to any restatements
- Companies must disclose whether they have a policy that prohibits hedging of company shares (e.g., through the purchase of derivatives that protect executives from stock price swings)
- Companies must disclose whether they have a policy to address pledging of company shares (e.g., as collateral for a loan)
The SEC has yet to release guidance on these areas and the timing of future guidance is uncertain. As such, many companies have taken steps to implement policies on their own.
Clawbacks
Dodd Frank requires a broader definition of clawbacks compared to Section 304 of SOX, which applies to CEOs and CFOs. When clawback policies were first adopted by Dodd Frank many companies took a “wait and see” approach; however, with the continued delay in final regulations, companies have been more proactive in modifying their policies.
Nearly all of our research companies – 94 of 100 (94%) – have some form of clawback policy, compared to 86% and 80% in 2011 and 2010, respectively. In 2012, 10 companies adopted a new policy and 11 modified existing provisions. The two industries that saw the most changes to their clawback polices included automotive (45% of companies) and financial services (45% of companies). Typically financial services firms expanded their clawback policies to cover all incentive awards and situations beyond just financial restatements.
As was the case in prior years, a financial restatement (83%) and misconduct (75%) are the most common triggers for a clawback.
Under nearly all policies, it is most common for companies to include the ability to recoup compensation previously granted and it is less prevalent to clawback any future incentive compensation. While the final rules are not expected to include future compensation, we expect companies that already have this provision may continue to include it.
|
Compensation Subject to Clawback |
2012 |
2011 |
2010 |
|||
|
No. of cos |
% of Cos. n=94. |
No. of cos. |
% of Cos. N=98 |
No. of Cos. |
% of Cos. n=89 |
|
|
Prior LTI |
88 |
95% |
95 |
97% |
79 |
89% |
|
Prior Annual Incentive |
86 |
92% |
92 |
94% |
81 |
91% |
|
Future Annual Incentive |
19 |
20% |
16 |
16% |
20 |
22% |
|
Future LTI |
18 |
19% |
15 |
15% |
14 |
16% |
Note: Percentages add up to greater than 100% due to multiple responses
Coverage extends to NEOs in 91% of companies, which is consistent with our findings in 2010 and 2011. Of the other 9% of companies, most define coverage as, “executive officers, officers, senior executives or senior management.” Companies are not required to disclose the level of program detail in the proxy, but we expect most program provisions are more broad-based.
Similar to our findings in 2010 and 2011, less than a quarter of companies indicate the length of the look-back period during which compensation can be recovered after a financial restatement. Of the 20 companies that disclosed a time frame, the most common is 1 year (47% of companies) from date of restatement, followed by 3 years (26% of companies). While not common practice, some companies disclose a different time period for annual incentives and long-term incentives.
While many companies are waiting for the SEC to adopt final rules before making comprehensive changes to their policies, companies have been proactive over the last 3 years in adopting clawback policies. On their own merits, such provisions:
- Provide the Board with flexibility to clawback for unforeseen circumstances
- Allow flexibility for the Board to access whether the reinstatement had implications for shareholders (e.g., economic issue or accounting issue)
- Increase executive accountability
- Garner positive reaction from shareholders
- Receive credit by ISS in the QuickScore evaluation (under Equity Risk Mitigation topic)
As we await for the SEC to propose final rules, there are several practical challenges to clawing back compensation, such as how to clawback equity gains, how to claw back from former employees and the tax implications of clawbacks.
HeDGING AND PLEDGING
Hedging and pledging have become shareholder/ corporate governance issues, especially now that ISS views any hedging and significant pledging by insiders to be indicative of a potential failure of risk oversight on behalf of a company’s Board. The Board’s policy regarding these practices is most commonly reflected in the company’s insider trading policy, but it can be addressed through Board resolutions or a stand-alone policy.
Hedging is viewed as a poor practice as it insulates executives from stock price movement and reduces alignment with shareholders. Pledging, in modest amounts, may not be viewed as negatively as hedging, yet can become problematic if there were a significant decline in stock price and which necessitated a sale of shares. Given the potential negative perception of insider hedging and pledging, companies have begun to adopt policies to limit these provisions. Anti-hedging and pledging policies are in place at 91% and 59% of companies studied, respectively; 59% of companies have both policies in place and 32% only have a hedging policy.
|
Hedging / Pledging Policy |
2012 |
|
|
No. of cos |
% of Cos. n=100 |
|
|
Hedging |
91 |
91% |
|
Pledging |
59 |
59% |
|
Both |
59 |
59% |
|
Hedging Only |
32 |
32% |
Note: Percentages add up to greater than 100% due to multiple responses
An example of typical disclosure of a prohibition on hedging/pledging is reflected in PepsiCo’s proxy disclosure:
“Our insider trading policy prohibits executive officers from using any strategies or products (such as derivative securities or short-selling techniques) to hedge against the potential changes in the value of PepsiCo Common Stock. In addition, executive officers may not hold PepsiCo securities in a margin account or pledge PepsiCo stock or PepsiCo stock options as collateral for a loan.”
Pledging was not addressed in Dodd-Frank per se, and we do not know what the SEC’s position will be in the future. We do however expect more companies to adopt pledging policies going forward given ISS’ 2012 policy statement that identified pledging of company stock by executives as a poor practice.
To improve Say on Pay results, many companies have already have already implemented policies that prohibit hedging and pledging.
Perquisites
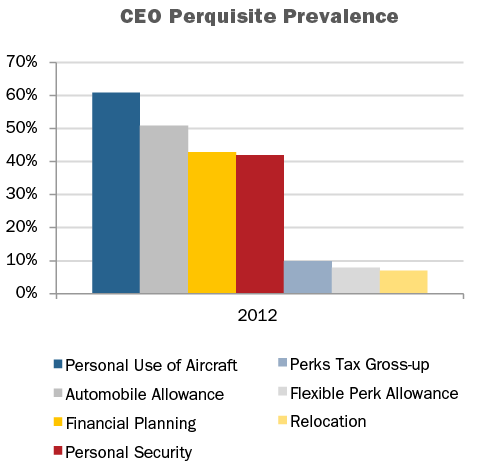
In 2012, companies in our research (91%) provided one or more perquisites to the CEO. Most commonly provided perquisites to the CEO include personal use of aircraft (61%), automobile allowance (51%), financial planning (43%) and personal security (42%).
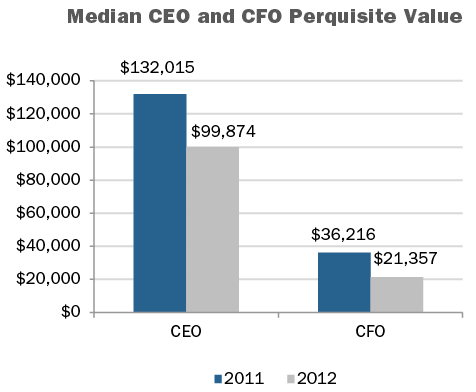
The value of perquisites offered to executives however, has continued to decrease. Median perquisite values disclosed for the CEO and CFO in 2012 were $99,874 and $21,357, respectively. This is a 32% decrease for CEOs and a 70% decrease in value for CFOs in our research. The manufacturing industry had the highest median perquisite values of $319,793 and $69,069 for the CEO and CFO, respectively.
Perquisites tend to be a small proportion of an executive’s total compensation, yet are often highly visible. Shareholders prefer to see pay delivered in performance-based vehicles vs. perquisite programs. Over the past few years, companies have been making changes to these programs in reaction to increased shareholder scrutiny and specific feedback received from shareholders or the likes of ISS or Glass Lewis. In 2012, 9 of 100 companies (9%) disclosed making a change to their perquisite program, a continuation of the trend to reduce perquisites that took hold several years ago.
|
Perquisite Change Reported in 2012 CD&A |
2012 |
2011 |
2010 |
|||
|
No. of Cos. |
% of Cos. n=9 |
No. of Cos. |
% of Cos. n=14 |
No. of Cos. |
% of Cos. n=20 |
|
|
Eliminated tax gross-ups on perquisites |
4 |
44% |
6 |
43% |
8 |
40% |
|
Eliminated perquisite |
2 |
22% |
9 |
64% |
11 |
55% |
|
Reduced perquisite program/value |
1 |
11% |
1 |
7% |
2 |
10% |
|
Changed perquisite program |
1 |
11% |
0 |
0% |
3 |
15% |
Note: Percentages add up to greater than 100% due to multiple responses
Occasionally, a company eliminates a perquisite and offsets some of the lost value or reduction through a salary increase or a one-time payment. An example from 2012 is Lear Corp, which disclosed the following:
“Effective January 1, 2012, we eliminated a separate annual perquisite allowance by adding this amount to the base salary of our Named Executive Officers. However, for purposes of determining incentive awards in 2012 and 2013, which are specified as a multiple of salary, the prior perquisite amount is excluded.”
Importantly, Lear excluded the amount of this increase for purposes of incentives, eliminating the potential to provide an even greater, unintentional increase, in total.
The changes in 2012 include two companies eliminating perquisite allowances, one company approving residential security measures for the CEO and one company reducing the allowance for personal use of aircraft for the CEO and CFO. We expect this trend to sustain as more and more companies are responding to the concerns of their shareholders, which can be voiced through a company’s Say on Pay vote.
Conclusions
With Say on Pay votes held annually for a majority of companies, we continue to see companies stay ahead of the curve and track “best practices” in order to satisfy shareholders and proxy advisory firms. This results in reevaluations of company pay and governance practices, and as our research shows, continued modification of perquisite programs and clawback policies, and adoption of hedging and pledging policies. The goal continues to be closer alignment of executive compensation with shareholder interests. We expect companies and Boards to more proactively monitor proxy advisory firm policies and Dodd-Frank legislation when considering changes to pay programs.
ISS Policy Update – RDA Test
For the past two years ISS has used three quantitative pay vs. performance tests related to CEO pay and company performance (absolute Pay-TSR Alignment / PTA; Multiple of Median / MOM; and Relative Degree of Alignment / RDA) to screen for companies where a potential pay-for-performance misalignment may exist. In addition to the quantitative screen, ISS will always conduct a qualitative analysis of the pay program. If Medium or High concern is identified through the quantitative pay vs. performance screen, the qualitative analysis will be more robust.
For 2014, ISS modified the RDA test. In the past the RDA screen had been calculated as the difference between the company’s TSR rank and the CEO’s total pay rank within a peer group, as measured over one-year and three-year periods. The one-year and three-year periods were weighted 40% and 60%, respectively. The new methodology is focused on three years only. In addition, the RDA policy updates indicates that companies with less than three years of pay and performance data will still be subject to the RDA test, which reflects a change versus past practice.
CAP Perspective: We agree with ISS’ decision to apply a longer-term focus to the quantitative RDA test; i.e., solely a three-year timeframe for both pay and performance. However, we believe that recent Committee decisions best relate to company performance over time.
Board Response to Majority Supported Shareholder Proposals
For 2014, ISS made three changes to its policy on Board responsiveness to majority-supported shareholder proposals.
- ISS will review the responsiveness of a Board to any shareholder proposal that receives one year of a majority of votes cast support (rather than the previous “triggers” of either two years of a majority of votes cast in a three-year period, or one year of a majority of shares outstanding);
- ISS adopted a case-by-case approach, including a list of factors for Analysts to consider, for assessing implementation of majority vote proposals;
- Finally, ISS provided Analysts with broader discretion when determining which directors to hold accountable in the event the level of responsiveness is found to be insufficient.
We note here that ISS included “the Board’s rationale as provided in the proxy statement” as one of the factors in the case-by-case analysis.
CAP Perspective: Using the proxy statement as a communication (marketing) document in addition to a compliance document has been an often stated best practice over the past few years, which gains additional support from this ISS policy update.
This “comply or explain” policy update from ISS encourages the Board to enact a majority supported shareholder proposal, but gives an important second route. We believe there are instances where the Board should be able to exercise its discretion to respond in a manner that it believes is in the best interest of the company. However, we believe that providing rationale in these instances is also important.
Conclusion
ISS policies and tests should not determine, but rather be one input to the compensation program design and annual decision making process. Therefore, an understanding of ISS’ policies and tests, both retrospectively and prospectively (projection) is important. We encourage our clients to review how ISS’ 2014 policy updates are likely to impact them.
CAP submitted comments to ISS on the draft policy updates, which can be found at: http://www.issgovernance.com/2014draftpolicycommentperiod.
Reflecting a change with past practice, ISS is opening a new consultation period on approaches to certain benchmark policies for consideration for longer term policy changes (beyond 2014). An example of the type of area that this will cover is evaluation of new share requests. As more information on the consultation period and related topics becomes available, we will update our clients. The current consultation period closes in February 2014, which will eventually be followed by the more traditional process which includes a policy survey followed by release of draft policies for comment.
Management Say-on-Pay Proposals (U.S.)
ISS will recommend voting against advisory Say on Pay resolutions related to executive compensation if there is a perceived misalignment between CEO pay and company performance, based on both quantitative tests and a qualitative review of the pay program and related Compensation Committee decisions.
ISS is considering the following policy change for 2014:
Simplify the methodology for calculating the Relative Degree of Alignment (RDA) pay-for-performance screen. The proposed new methodology is to calculate the difference between the subject company’s TSR rank and the CEO’s total pay rank within a peer group, as measured over a three-year period (or for as many fiscal years that the company has been publicly traded and has disclosed pay data, if less than three years).
Currently the RDA screen is calculated as the difference between the company’s TSR rank and the CEO’s total pay rank within a peer group, as measured over one-year and three-year periods. The one-year and three-year periods are weighted 40% and 60%, respectively.
ISS Request for Comment – Proposed RDA Policy Change
Are there circumstances under which performance or pay from the most recent year should weigh more heavily in a pay-for-performance analysis?
CAP Perspective: We agree with ISS’ preliminary decision to apply a longer-term focus to the quantitative RDA test; i.e., solely a three-year timeframe for both pay and performance. However, we believe that recent Committee decisions best relate to company performance over time. We urge ISS to state that the qualitative assessment will place particular emphasis on recent Committee decisions that apply prospectively in a year following:
- Below par shareholder support for an advisory Say on Pay resolution (less than 70%)
- A CEO transition
- A corporate transformation (merger, major acquisition, etc.)
We also urge ISS to use realizable pay in the RDA test (with ISS’ current definition and assumptions), instead of grant date pay. Realizable pay would better show if pay was aligned with performance over time. This methodology change could also apply to the PTA test.
Finally, we urge ISS to address the following questions and concerns in its 2014 policy release.
- Under the ISS 2014 policy, as proposed, a three-year point-to-point TSR will be used for the quantitative RDA test, which in practice reflects a compound annual growth rate. This approach could lead to volatile RDA results since it uses a single day as the starting point and ending point in the performance analysis. An alternative approach that ISS should consider is to calculate TSR using the average starting and ending stock prices over a 20-trading-day period. This will reduce volatility and add credibility to the results.
- ISS should also consider adopting an alternative approach for calculating TSR performance that reflects the average relative position of TSR during each of the three most recent one-year periods, rather than a compound annual growth rate. Looking at performance trends over multiple time periods may yield additional insight into performance and related pay decisions.
- Also under the ISS 2014 policy, as proposed, three-year average (arithmetic mean) compensation will be used in the RDA test. We support this approach, but certain issues should be acknowledged. This approach does not fully address the problematic timing of proxy reporting where a Compensation Committee evaluates performance in the year just ended and makes a long-term incentive award in the beginning of the following year. This award is reported in the proxy in the following year and does not impact ISS’ analysis. We urge ISS to acknowledge that this timing (reporting) difference will be considered in its qualitative assessment of the pay program and related decision making. Given the imperfections in the compensation data analyzed, we support the simple, straightforward approach that is proposed for the compensation data included in the RDA quantitative test that focuses solely on a longer time horizon vs. the current approach. The approach, as proposed, will also smooth out some of the extremes seen in individual years.
- We ask ISS to provide its reasoning as to why it is appropriate to weigh recent pay and performance more in the PTA test, but not in the RDA test. Why does it make sense for these tests to incorporate inconsistent timeframes and weightings?
ISS Request for Comment – Proposed RDA Policy Change (cont’d)
Are there any unintended consequences from using a simple, unweighted three-year pay and performance measure as the basis for the RDA screen?
CAP Perspective: We believe the proposed approach for performance measurement is potentially too volatile since it depends heavily on a single “start” point and a single “end” point.
As stated above, we urge ISS to use an average stock price at the beginning and end points of the TSR calculations for its pay versus performance tests, which would align with methodology used in the ISS SVT tool. We believe that use of a 20-trading-day average stock price would limit the impact of very short-term stock price fluctuations on the results.
A second alternative, also noted above, would be to use the average relative position of TSR during each of the three most recent one-year periods, rather than a compound annual growth rate. This would be beneficial since it would reduce volatility in the TSR calculation.
ISS Request for Comment – Other
Please feel free to add any additional information or comments on the proposed policy change.
CAP Perspective: We have additional comments that relate to ISS Say on Pay vote recommendations. Outlined below, we describe additional changes that we urge ISS to consider.
RDA and PTA Tests – Time Period
We urge ISS to provide its reasoning for why the timeframe used for the RDA quantitative test (three years) is different than the timeframe used for the PTA quantitative test (five years). Why is the use of inconsistent time frames appropriate?
RDA Quantitative Thresholds
ISS has indicated that the thresholds for the Medium and High level of quantitative concern have not yet been set by ISS Research for 2014 pay vs. performance analyses. We urge ISS to expand the thresholds for the RDA test so that fewer companies are flagged with “Medium” or “High” concern levels and, in turn, increase consistency between the RDA test and the PTA test.
In the December 20, 2011 ISS white paper titled “Evaluating Pay for Performance Alignment”, in the “Back-testing the Measures” section, a table was included:
|
Measure |
Level that may trigger high concern in conjunction with other measures (“Medium” concern) |
Level that triggers high concern by itself |
|
RDA |
-30 (~25th percentile) |
-50 (~10th percentile) |
|
MOM |
2.33x (~92nd percentile) |
3.33x (~97th percentile) |
|
PTA |
-30% (~10th percentile) |
-45% (~5th percentile) |
As shown above, 1 in 4 companies is expected to receive “Medium” concern from the RDA test, but only 1 in 10 companies is expected to receive “Medium” concern from the PTA test.
- We believe the amount of companies expected to receive “Medium” and “High” concern within each of ISS’ quantitative screens should be more consistent
- We find the thresholds (~10th percentile and ~5th percentile) in the PTA test to be most reasonable to identify outliers, and believe expecting one in four companies to receive “Medium” concern from the RDA test is unreasonably high
Performance Goals – Evaluation of “Rigor”
ISS reviews the rigor of performance goals in its qualitative pay-for-performance assessment. We urge ISS to be more transparent regarding the parameters for this assessment.
Multi-year Long-term Grants
When recruiting new CEOs, companies often grant long-term incentives that are intended to make up for compensation forfeited from a previous employer (often called “make-whole” grants). In these instances, we urge ISS to exclude these grants from the pay-for-performance testing since the grants fill a very specific need and would not be granted in the absence of forfeited compensation.
Time-based Stock Options
In our experience, many investors and most corporate directors view time-based stock options as a performance-based long-term incentive vehicle; i.e., they disagree with ISS’ classification of this form of compensation as “non-performance-based pay”. We urge ISS to include questions on this topic in its next policy survey.
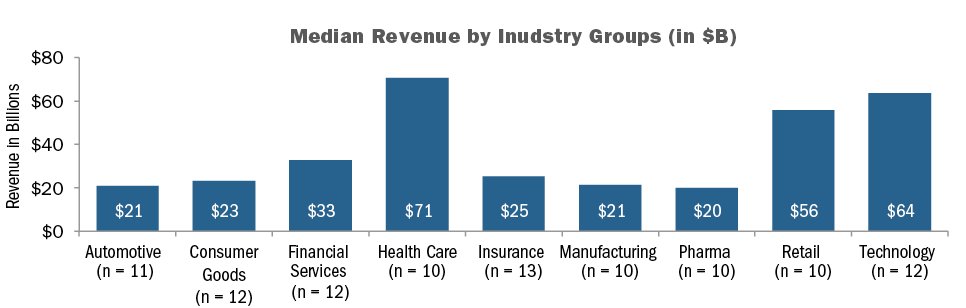
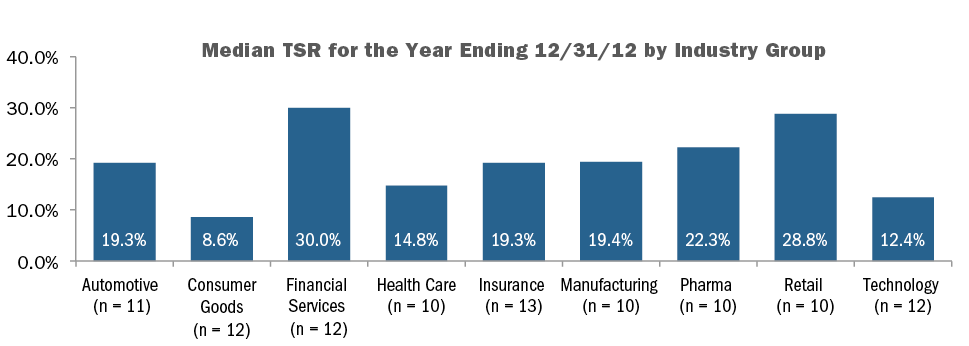
Among the 100 company sample, median revenue was $33B, median market capitalization was $37B and median Total Shareholder Return (TSR) was 19% in 2012. As indicated in the charts below, there is significant variation in company size and performance by industry.
COMPENSATION PHILOSOPHY
Nearly 60% of companies in our study disclose a target total pay position for the Named Executive Officers (“NEOs”). Of these companies, approximately 75% target total pay at median, up from 60% a year ago; indicating that companies are shifting their compensation pay philosophy to a market median standard in reaction to increased scrutiny from shareholders and proxy advisory firms.
|
Target Total Compensation Pay Positioning (n=57) |
CEO |
CFO |
|
Below Median |
1% |
0% |
|
At Median |
74% |
75% |
|
Above Median |
25% |
25% |
CAP Perspective: Change in targeted pay position to median reflects movement to adopt more conservative target pay practices that demonstrate a strong link to performance.
PAY MIX
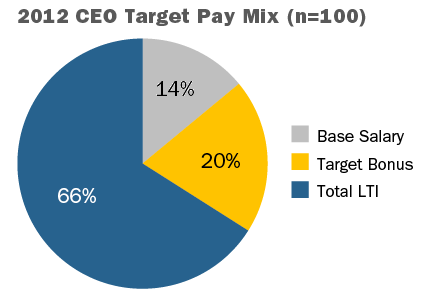
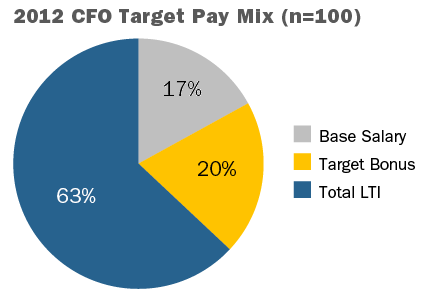
Overall, companies did not make significant shifts in the total pay mix in 2012 vs. 2011. CEO and CFO total pay continues to place significant emphasis on long-term incentives (“LTI”); on average, LTI reflects 66% of pay for CEOs and 63% for CFOs.
CHANGES IN TARGET PAY LEVELS
The chart below shows average year over year change in target pay levels for CEOs and CFOs in our study. 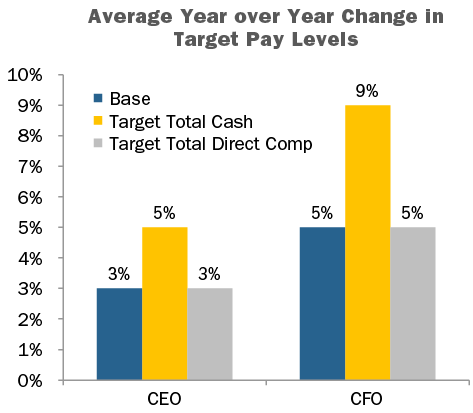
Note: Excludes newly hired/promoted executives and one-time sign-on/retention equity awards. Percentages include zeroes.
CAP Perspective: We see increases in target pay levels in the low single digits, though the most significant increase is in target annual incentive opportunities suggesting that companies are increasing performance-based pay to reinforce the pay-for-performance link.
Base Salary
CEO base salaries in 2012 increased 3%, on average, though only 46% of companies provided salary increases. Base salaries for CFOs increased by 5% though fewer companies provided an increase in 2012 (68%) vs. 2011 (78%) suggesting salary increases were made less frequently for senior executives than other employees.
Executives in the Health Care and Pharmaceutical industries were more likely to receive a salary increase (70% of CEOs in the Health Care industry and 90% of CFOs in the Pharmaceutical industry) than those in other industries. Financial Services, Insurance and Technology industries were less likely to provide a salary increase for the CEO in 2012.
|
Base Salary Action |
CEO |
CFO |
||
|
2012 |
2011 |
2012 |
2011 |
|
|
Increase |
46% |
47% |
68% |
78% |
|
No Change |
52% |
50% |
26% |
20% |
Note: Does not include newly hired CEOs or CFOs. Therefore, percentages do not add up to 100%.
Target Bonus
Target bonus for both the CEO and CFO increased modestly at median levels. At the 75th percentile, the bonus opportunity for CFOs increased by almost 20 percentage points. Target bonuses for CEOs in the Automotive, Consumer Goods and Technology industries increased the most in 2012. CFOs in the Automotive, Retail and Technology industries saw significant increases as well.
|
Summary Statistics |
Target Bonus as a % of Salary |
|||||
|
CEO |
CFO |
|||||
|
2012 |
2011 |
Change in %age Pts. |
2012 |
2011 |
Change in %age Pts. |
|
|
75th Percentile |
200% |
200% |
0% |
143% |
125% |
+18% |
|
Median |
157% |
153% |
+3% |
103% |
100% |
+3% |
|
25th Percentile |
133% |
135% |
-2% |
90% |
85% |
+5% |
Target Total Cash Compensation
Target total cash compensation increased for both the CEO (5%) and CFO (9%) in 2012, mainly due to increases in annual incentive opportunities.
Total Long-term Incentives (LTI)
Increases in total LTI in 2012, on average, were fairly modest; total LTI increased by 3% for CEOs and 5% for CFOs. However, some industries saw significant increases in LTI year over year: CEOs in the Health Care and Consumer Goods industries, on average, received increases in LTI of 30% and 20%, respectively. CFOs in the Technology and Retail industries received the highest increases of 24% and 9%, respectively.
Target Total Compensation
Target total compensation increased over 2011 levels primarily through increases in target annual incentives and, in some industries, through increases in LTI. These findings varied by industry. Financial Services, Pharmaceutical and Retail companies, on average, provided the most significant increases in target annual incentives over other pay components, while Consumer Goods and Health Care industries had the greatest increase in target LTI opportunities.
CONCLUSIONS
Overall, companies had modest increases in target pay levels for the CEO and CFO, through changes in annual and long-term incentives. The Consumer Goods and Health Care industries saw increases in the 15%-20% range driven by higher LTI opportunity while other industries saw more modest changes in total pay levels. Compensation philosophies continue to migrate to median as companies adopt a more conservative pay philosophy. Overall pay mix for the CEO continues to maintain a strong LTI component (66% of pay) with salary representing smaller component of pay (14%), on average. We expect shareholders and proxy advisory firms to continue to influence company pay strategy, as companies to continue to provide modest increases in target total pay mainly through incentive compensation.
|
Industry |
Average Year over Year Change in CEO Target Pay – Top 3 Industries and Overall Sample |
|||
|
Base |
Target Bonus |
LTI |
Target Total Compensation |
|
|
Health Care |
2% |
4% |
30% |
19% |
|
Consumer Goods |
3% |
13% |
20% |
17% |
|
Automotive |
4% |
7% |
7% |
6% |
|
Overall Sample |
3% |
8% |
3% |
3% |