Highlights
- Nearly all companies (94%) have adopted a clawback policy, even without SEC guidance on Dodd Frank requirements for clawbacks
- Consistent with our past findings, the most common forms of compensation that are potentially subject to recoupment are prior year’s cash and stock incentives
- Hedging policies are in place at most companies, with 95% disclosing a hedging policy (vs. 91% in 2013)
- Pledging policies can vary in scope as companies, but 63% of companies have a policy of some type in place
- Some companies ban all pledging (68%), while others require advance approval for pledged shares (20%) or only prohibit pledging of shares subject to stock ownership guidelines (12%)
Survey Sample
Compensation Advisory Partners (“CAP”) reviewed 2014 proxy disclosures at a sample of 100 companies among the Fortune 500 representing nine industry groups. Industry groups included: Automotive, Consumer Goods, Financial Services, Health Care, Insurance, Manufacturing, Pharmaceutical, Retail, and Technology. For the companies studied, the median revenue size and market capitalization was $32B and $52B, respectively. The median 2013 total shareholder return (TSR // change in stock price plus dividends) was 43%.
Clawbacks
Although companies are still waiting for SEC guidance on Dodd Frank, many have already implemented clawback policies on their own. Dodd Frank requires a broader definition of clawback compared to Section 304 of SOX, which applies to CEOs and CFOs.
Similar to our findings last year, 94% of companies we studied have some form of clawback policy, compared to 86% and 80% in 2011 and 2010, respectively. Because the majority of companies have now adopted robust clawback policies, the number of changes made in 2013 as compared to prior years has decreased. In 2013, there were no companies that adopted a new clawback policy, while only 7 modified existing provisions. The most common changes made were to expand the compensation subject to clawbacks and expand the triggers for clawbacks beyond financial restatements.
As in prior years, a financial restatement (87%) and misconduct (77%) are the most common triggers for a clawback. For the first time in our study, fraud (50%) will trigger a clawback for a majority of the companies analyzed.
Under nearly all policies, it is most common for companies to include the ability to recoup compensation previously granted. Some companies will also have clawback provisions in place that allow them to either adjust the amounts of future incentive compensation given or cancel any outstanding performance-based stock or cash awards.
|
Compensation Subject to Clawback |
2013 |
% of Cos. |
2012 |
% of Cos. |
2011 |
% of Cos. |
2010 |
% of Cos. |
|
Prior LTI |
91 |
98% |
88 |
95% |
95 |
97% |
79 |
89% |
|
Prior Annual Incentive |
89 |
96% |
86 |
92% |
92 |
94% |
81 |
91% |
|
Future Annual Incentive |
20 |
22% |
19 |
20% |
16 |
16% |
20 |
22% |
|
Future LTI |
21 |
23% |
18 |
19% |
15 |
15% |
14 |
16% |
Note: Percentages add up to greater than 100% due to multiple responses
Coverage extends to all NEOs in 97% of companies, which is higher than our findings in 2010, 2011, and 2012. Interestingly, many companies extend coverage beyond the NEO level, with 50% of companies having clawback policies in place for all Section 16 officers. Companies are not required to disclose the level of program detail in the proxy, but we expect most program provisions are more broad-based.
Similar to our findings in prior years, less than a quarter of companies indicate the length of the look-back period during which compensation can be recovered. Of the 21 companies that disclosed a time frame, the most common is 1 year (52% of companies) from date of restatement, followed by 3 years (38% of companies).
As we wait for the SEC to propose final rules, there are several practical challenges to clawing back compensation, such as how to clawback equity gains, how to claw back from former employees and the tax implications of clawbacks.
Hedging and Pledging
With increasing scrutiny from shareholder services such as ISS, hedging and pledging policies have become more significant governance / shareholder issues. ISS has taken the stance that any hedging and significant pledging by insiders to be indicative of a potential failure of risk oversight on behalf of a company’s Board. The Board’s policy regarding these practices is most commonly reflected in the company’s insider trading policy, but it can be addressed through Board resolutions or a stand-alone policy.
Hedging is viewed as a poor practice as it insulates executives from stock price movement and reduces alignment with shareholders. Pledging, in modest amounts, may not be viewed as negatively, yet can become problematic if there were a significant decline in stock price which necessitated a sale of shares from a senior executive. Given the potential negative perception of insider hedging and pledging, as well as the pending Dodd Frank guidance, companies have begun to adopt policies to limit these provisions. Anti-hedging and pledging policies are in place at 95% and 63% of companies studied, respectively; 63% of companies have both policies in place and 32% only have a hedging policy.
|
Hedging / Pledging Policies |
2013 |
% of Cos. n=100 |
2012 |
% of Cos. |
|
Hedging Policy |
95 |
95% |
91 |
91% |
|
Pledging Policy |
63 |
63% |
59 |
59% |
|
Both |
63 |
63% |
59 |
59% |
|
Hedging Only |
32 |
32% |
42 |
42% |
Note: Percentages add up to greater than 100% due to multiple responses
An example of typical disclosure of a prohibition on hedging/pledging is reflected in 3M’s proxy disclosure:
“The Company’s stock trading policies prohibit directors and the Company’s executive officers from (i) purchasing any financial instrument that is designed to hedge or offset any decrease in the market value of the Company’s common stock, including prepaid variable forward contracts, equity swaps, collars and exchange funds; (ii) engaging in short sales related to the Company’s common stock; (iii) placing standing orders; (iv) maintaining margin accounts; and (v) pledging 3M securities as collateral for a loan.”
Our analysis of pledging policies was broken down further to show that there are variations to prohibit pledging. A company can ban all pledging (68% of companies with anti-pledging policies), prohibit pledging of shares unless an employee receives advance approval (20%) or prohibit any shares subject to stock ownership guidelines to be pledged (12%).
An example of the latter two anti-pledging policies can be found in Best Buy and ACE’s proxy statements, respectively:
Best Buy: “…our executive officers and Board members are prohibited from holding Company securities in a margin account or pledging Company securities as collateral for a loan, unless approved in advance by the Compensation Committee.”
ACE: “The Company prohibits NEOs from pledging shares that are held in satisfaction of the share ownership guidelines.”
Pledging was not addressed in Dodd-Frank per se, and we do not know what the SEC’s position will be in the future. We do however expect more companies to adopt pledging policies going forward given ISS’ 2012 policy statement that identified pledging of company stock by executives as a poor practice.
Conclusions
We continue to see companies stay ahead of the curve and track “best practices” in order to satisfy shareholders and proxy advisory firms. This results in reevaluations of company pay and governance practices, and as our research shows, continued modification of clawback policies, and adoption of hedging and pledging policies. While formal guidelines have not been given to date, companies are adopting these policies as good governance, regardless of any final SEC guidance.
Highlights
- The look and feel of proxy statements have changed
- Best practices for CD&A include a concise executive summary
- Pay mix charts, other charts, a list of “best practices” that the issuing company follows and a proxy summary are now commonly included
- Financial performance frames the discussion of executive compensation
- A trend in recent years is the disclosure of realized/realizable pay
Compensation Discussion & Analysis (CD&A)
Survey Sample
Compensation Advisory Partners (“CAP”) reviewed 2014 proxy disclosures at a sample of 100 companies among the Fortune 500, representing nine industry groups. Industry groups included: Automotive, Consumer Goods, Financial Services, Health Care, Insurance, Manufacturing, Pharmaceutical, Retail, and Technology. For the companies studied, the median revenue size and market capitalization was $32B and $52B, respectively. The median 2013 total shareholder return (TSR // change in stock price plus dividends) was 43%.
The Say on Pay vote has succeeded in improving and increasing communication with shareholders regarding executive compensation programs. Many companies have adopted what are commonly referred to as “best practices” for proxy disclosure.
|
Elements Included in 2014 Proxy Disclosure Among Fortune 500 companies |
||
|
# of Cos |
% of Cos |
|
|
Executive Summary |
89 |
89% |
|
Pay Mix Chart(s) |
79 |
79% |
|
Use of Other Charts and/or Graphics |
73 |
73% |
|
List of “Best Practices” |
67 |
67% |
|
Realized and/or Realizable Pay |
15 |
15% |
- Executive Summary: Most important part of the CD&A. Continued enhancement over past few years. Typically includes thorough discussion of financial performance and key company achievements, a summary of CEO compensation, and key changes to executive compensation programs, if any
- Pay Mix Charts: Very common. Typically reflect variable vs. fixed pay or performance-based vs. non-performance-based pay
- Use of Other Charts and/or Graphics: Very common. Most often used to directly, and concisely, describe company performance. May include absolute and/or relative performance
- Realized Pay and Realizable Pay: Emerging practice. Intended to illustrate the impact of performance outcomes on pay over time. In contrast, while the Summary Compensation Table reflects actual cash payments, equity awards reflect target values
- List of “Best Practices”: Very common. Often takes the form of “What We Do/Don’t Do” list. Eliminates need for shareholders to take the time to seek these things out
Another trend related to enhanced proxy disclosure of executive compensation programs and decision-making, is increased disclosure of incentive plan goals. Shareholders and proxy advisory firms have expressed the desire for more information on short- and long-term incentive compensation performance targets/goals. Two examples of companies that increased proxy-based incentive plan goal disclosure in reaction to shareholder input are Coca-Cola and Dow Chemical.
|
Company |
Shareholder Feedback |
Action by Company |
|
Coca-Cola |
|
|
|
Dow-Chemical |
|
|
Conclusions
We have observed companies more frequently modifying and enhancing their executive compensation and governance practices, given increasing influence and input of shareholders (and proxy advisory firms). Shareholder communication has also been enhanced, including the proxy statement.
During the 2015 proxy season, we expect more companies to disclose realizable and/or realized pay, particularly if TSR or Say on Pay support are low, and enhance transparency and highlight best practices in executive compensation disclosure. The goal is for executive compensation programs to best support business strategy, while aligning with shareholder interests. Disclosure is an opportunity to highlight all the good work and thought that goes into the design of these programs and the related decision-making.
The SEC recently updated its regulatory agenda. As part of the update, the deadline to adopt final pay ratio rules was pushed back to October 2015 (from October 2014).
- Implication: companies with a Dec 31 fiscal year end are not expected to be required to comply with pay ratio rules/disclosure until publication of 2017 proxy statements
The deadline for other outstanding compensation-related rulemaking coming out of the Dodd-Frank Act was also delayed to October 2015: standardized pay vs. performance disclosure, hedging policies, and clawbacks requirements.
- Note: Timeline changes reflect a new deadline, not the date at which rulemaking will be published or adopted
We will provide additional updates as this issue continues to evolve.
Key CAP Findings
Board Compensation. little/no change
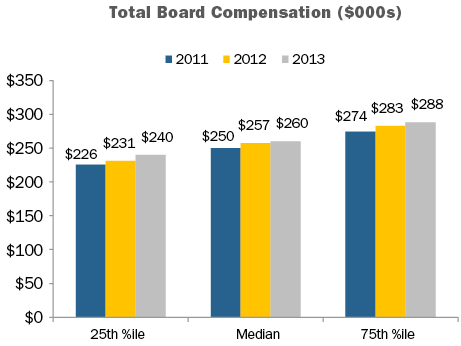
- Total Fees. At median, flat from 2012 to 2013 ($257K vs. $260K)2. Only increased four percent since 2011.
- Retainers. Pay programs have been simplified, now viewed more as an “advisory fee” than an “attendance fee.” In general, companies have moved to a fixed retainer pay structure, with a component in cash and a component in equity.
- Meeting fees. Provided by only 15 percent of companies, down slightly from 2012.
- Equity. Full-value awards (shares/units) are most common. Only five percent of companies use stock options. 92 percent of companies denominate equity awards (stock or options) as a fixed value, versus a fixed number of shares.
- Pay Mix. On average, 56% equity-based vs. 44% cash-based (consistent for past three years). Alignment with long-term shareholders is reinforced by delivering a majority of compensation in equity.
Committee Member Compensation. little/no change
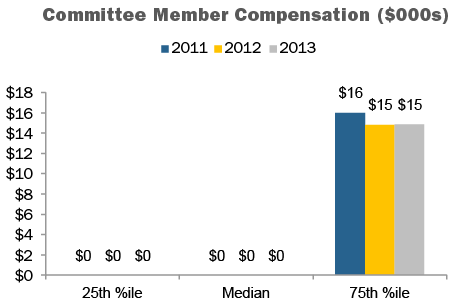
- Less than half of companies paid committee-specific member fees3.
- At median, committee member compensation is $04. There has been a trend away from committee member fees; value typically rolled into Board cash or equity retainers.
Committee Chair Compensation. limited, but notable change
- Nearly all companies provided additional compensation to committee Chairs, versus committee members, typically through an additional retainer. The additional compensation recognizes additional time requirements, responsibilities, and reputational risk.
- At median, $20K in additional compensation (vs. members) was provided to Audit and Compensation Committee Chairs, and $15K to Nominating/Governance Chairs. This is the first year the premium, at median, provided to Compensation Chairs equaled that provided to Audit Chairs.
Independent Board Leader Compensation.
limited, but notable change
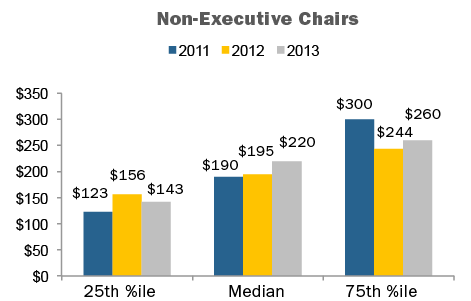
- Non-Exec Chair. Additional compensation is provided by all companies with this role, $220K at median.
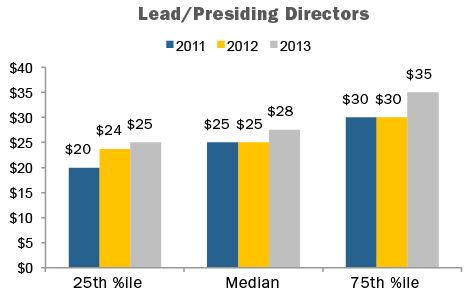
- Lead Director. Additional compensation is provided by nearly all companies with this role5, $28K at median. The differential in pay versus non-executive Chairs is in line with typical differences in responsibilities. Additional compensation was steady, at median, at $25K for the five years prior to 2013.
Perquisites. little/no change
- Overall, limited practice. One-third of companies continue to provide gift matching/charitable contribution.
Pay Limits. NEW to study
- Due mainly to advancement of litigation in Delaware court related to director compensation, several companies (23%) have adopted shareholder approved director compensation limits ($800K, at median). The limit most often applies only to equity-based compensation.
CAP Perspective
Board Pay Levels and Structure
We have hit somewhat of a “steady state” in terms of director pay levels. Over the next few years, we expect modest pay level changes; i.e., low-to-mid single-digit annual increases in Total Board Compensation6. among the broader data set. Individual companies typically make pay level changes every two-to-three years; when they do, the changes tend to be larger than those observed annually within the full data set.
In terms of practices, pay programs have continued a trend towards simplification, as director compensation has become viewed more as an “advisory fee” than an “attendance fee.” Companies have moved to fixed retainer pay structures, with a component in cash and a component in equity, as opposed to use of per-meeting fees.
Director Pay Limits
A number of companies have recently placed limits on director compensation. The limits are largely due to advancement of litigation in Delaware court. In these cases the issue has been that directors approve their own annual compensation, and the shareholder approved long-term incentive plan did not provide “meaningful limits” on the maximum award that could be granted to a director.
When seeking shareholder approval for amendment to an omnibus long-term incentive plan or director compensation plan, 23 percent of companies studied have included value- or share-based limits (13% and 10%, respectively) for non-employee director compensation. These limits range from $250K to $2 million, $800K at median, and typically apply to just equity-based compensation. Some companies have applied the limits to both cash and equity-based compensation while others have excluded initial at-election equity awards, committee Chair pay, and/or additional pay for Board leadership roles from the limit.
We expect prevalence of director pay limits to increase, becoming majority practice within the next three to four years.
Lead Director Compensation
The Lead Director role has evolved, oftentimes a more active role than three to five years ago. As a result, companies are looking at time commitment and responsibilities, and structuring compensation to appropriately reflect the current role and expectations. Boards are engaging in more outreach and meeting with shareholders to talk about governance practices, CEO succession and executive compensation, among other issues, and many investors want to hear from the Lead Director.
Prevalence of providing additional compensation for the Lead Director role has increased over the past five years. Currently, additional compensation is provided by nearly all companies studied with a Lead Director7.
Despite the increased activity of Lead Directors, additional compensation provided for the role continues to be quite different than non-executive Chairs. At median, $28K was provided for the Lead Director role, versus $220K for the non-executive Chair role. In terms of additional compensation, for Lead Directors the pay ranges from $25K to $35K and for non-executive Chairs it ranges from $143 to $260 at 25th and 75th percentiles, respectively. The differential in pay is in line with typical differences in responsibilities. Previously, additional compensation for Lead Directors was steady, at median, at $25K for the last five years. Still, differences exist, somewhat, in role/responsibilities across companies which can impact the level of premium compensation provided for the Lead director role.
Making the decision to provide additional compensation to the Lead Director can send a signal to investors regarding expectations for the role, including time commitment, responsibilities, and authority. Many times, companies have been able to settle (or argue against) shareholder proposals to split the CEO and Chairman roles by instituting (or emphasizing) a strong Lead Director and delineating the specific responsibilities of the position. Boards can also reassure investors concerned about overall governance practices at a company by increasing the Lead Director role/responsibilities. Stock Ownership Guidelines Based on our research, 83% of companies have formal stock ownership requirements. Approximately half of companies studied required directors to defer recognition of equity pay until retirement. The median value of required stock ownership level was $450K.
Detailed Findings
Total Board Compensation
At median, 2013 non-employee director compensation was $260K, generally consistent with 2012.
Pay Mix
The mix of cash and equity paid to outside directors has remained the same for the last 3 years. On average, 56 percent of compensation was equity-based, and 44 percent was cash-based.
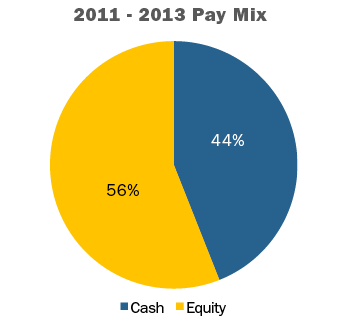
Equity Compensation
Full-value equity awards (stock/units) are the most common form of stock-based compensation. Only five percent of companies used stock options in 2013.
|
Vehicle |
2013 |
2012 |
2011 |
|
Full-Value Equity |
95% |
93% |
93% |
|
Stock Options |
2% |
2% |
5% |
|
Both |
3% |
5% |
2% |
Equity awards denominated as a fixed value, as opposed to awards based on a fixed number of shares, continue to increase in prevalence. In 2013, 92 percent of companies denominated equity awards – stock and/or options – based on a fixed value.
|
Award Type |
2013 |
2012 |
2011 |
|
Fixed Value |
88% |
82% |
84% |
|
FIXED Shares |
8% |
11% |
15% |
|
Both |
4% |
7% |
1% |
Committee Compensation
In 2013, just under half of companies studied paid fees specific to committee members (Audit – 48%, Compensation – 35%, and Nominating/Governance – 32%). Given this, at median, committee member compensation was $0. Among companies that do pay separate fees for committee member service, median compensation during 2013 was $15K.
During 2013, additional compensation (premium vs. member) was provided to 96 percent of Audit Committee Chairs, 90% of Compensation Committee Chairs, and 89% of Nominating/Governance Committee Chairs.
Unlike prior years, during 2013 the additional compensation provided to Audit Committee Chairs, at median, was equal to that provided to Compensation Committee Chairs ($20K). The premium provided to Chairs of Nominating/Governance Committees, at median, was lower ($15K).
Lead/Presiding Directors and Non-Executive Board Chairs
Additional compensation is typically provided to Lead/Presiding Directors and non-Executive Board Chairs.
During 2013, median additional pay provided to Lead Directors and non-executive Chairs increased to $28K and $220K, respectively. Previously, median compensation provided to Lead Directors had been flat for five years.
Best in Class Director Compensation Process & Practices
|
Best in Class Director Compensation PROCESS |
|
|
Best in Class Director Compensation PRACTICES |
|
- 1 Analysis excludes privately held companies.
- 2 Total Board Compensation reflects all cash and equity compensation for Board and committee service, excluding compensation for leadership roles such as committee Chair, Lead/Presiding Director, or non-executive Board Chair.
- 3 Audit, Compensation and/or Nominating and Governance committee members.
- 4 Reflects all compensation for committee member service (excludes additional fees for leadership roles), across all Board committees.
- 5 Excludes controlled companies. Also excludes instances where Lead Director role is assumed by Chair of Nominating and Governance Committee, who receives additional compensation for that role.
- 6 Total Board Compensation reflects all cash and equity compensation for Board and committee service, excluding compensation for leadership roles such as committee Chair, Lead/Presiding Director, or non-executive Board Chair.
- 7 Excludes controlled companies. Also excludes instances where Lead Director role is assumed by Chair of Nominating and Governance Committee, who receives compensation for the role.
- Cost of Plan (45% Weighting) – This component will be driven by the SVT model, though ISS will be looking at the cost of plans based on two approaches
- Grants outstanding + shares available for grant + new shares being requested
- Shares available for grant + new shares being requested
- ISS is using this dual approach so as not to put companies who have significant options outstanding at a disadvantage when requesting new shares
- Grant Practices (35% Weighting) – This component will consider burn rate as well as the form of recent grants for the CEO as well as other factors (see ISS link below for complete list)
- Plan Features (20% weighting) – This component will consider factors such as single vs. double trigger on change in control, minimum vesting period, authority for Board to use discretion to vest equity (see ISS link below for complete list)
The results of the scorecard will be compared to relevant benchmark comparison groups[2]. For further details on the EPSC and non-compensation related policies, please visit http://www.issgovernance.com/file/policy/2015USPolicyUpdates.pdf. In addition, to read about CAP’s views on these policies, you can review the comment letter we submitted to ISS at: https://www.capartners.com/news/194/61/Comments-on-ISS-Draft-2015-Proxy-Voting-Policies-U-S
Glass Lewis Released Additional Context and Expectations For “One-Off” Awards
In its 2015 U.S. policy updates related to compensation, Glass Lewis included discussion of how it will analyze special “one-off” awards (e.g., special grants of long-term incentives). While being “wary” of such awards, Glass Lewis has left room to find such awards reasonable with robust disclosure.
“We generally believe that if the existing incentive programs fail to provide adequate incentive to executives, companies should redesign their compensation programs rather than make additional grants…In certain circumstances additional incentives may be appropriate… companies should provide a… convincing explanation of their necessity…”
In its 2015 policy release, Glass Lewis also included some clarification regarding its qualitative and quantitative Say on Pay analysis. For the complete guidelines, visit: http://www.glasslewis.com/assets/uploads/2013/12/2015_GUIDELINES_United_States.pdf
[1] Shareholder Value Transfer assesses the cost of an equity plan relative to a company’s market cap and then compares the cost to industry benchmark
[2] S&P 500, Russell 3000, Non-Russell 3000, Bankrupt companies, recent IPOs as applicable. Burn rate / SVT will be industry specific
The increases that CAP observed in 2013 are much higher than seen last year. In 2012, our study showed almost no change in CEO compensation (-0.3% at median) and a very modest increase in CFO total direct compensation (1.4% at median).
Our findings indicate that the rate of increase in total direct compensation levels for both CEOs and CFOs accelerated in 2012-2013 compared to flat pay increases in 2011-2012. This increase suggests that the economic recovery is having an impact. The higher increase in 2013 among CEOs was driven by larger increases in actual bonuses paid for 2013 and slight increases in long-term incentives (LTI). The slower rate of growth in CFO compensation may signal a leveling off of CFO pay increases – which has been increasing at a faster rate than CEO pay since 2010. On an absolute basis, CFO total direct compensation continues to total approximately one-third of CEO total direct compensation.
Methodology
Our findings are based on a sample of 92 public companies. Similar to prior years, the study analyzes executive pay data disclosed by companies with revenues ranging from $1 to $130 billion, and median 2013 revenues of $8 billion. Only companies with the same CEO and CFO incumbents in the past three years are included allowing us to measure year-over-year changes for individual incumbents. In the past, we excluded financial services firms from the study, since this industry’s compensation practices were evolving in the years after the financial crisis. This year we expanded our sample to include financial services companies in our analysis, because we believe that compensation in the financial services industry has stabilized over the last couple of years.
Study Results
Salaries
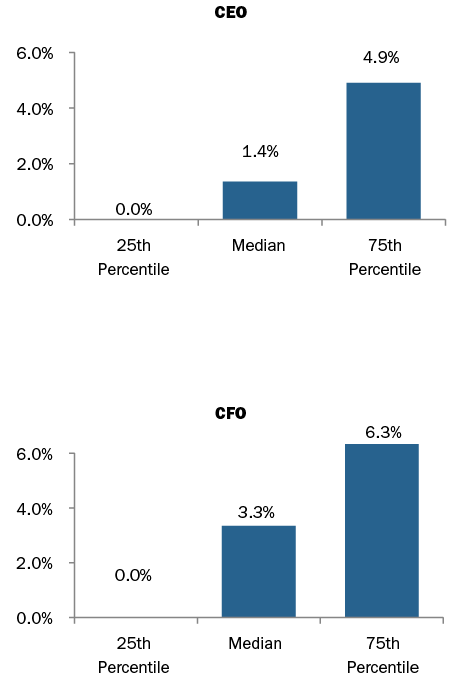
In 2013, approximately 73% of CFOs received salary increases compared to 85% in 2012. The median increase was 3.3% and the 75th percentile increase was 6.3%. In comparison, only 54% of CEOs received salary increases and the increases were smaller — 1.4% at median and 4.9% at the 75th percentile. The number of CEOs receiving a salary increase was similar to 2012. Less frequent and lower salary increases among CEOs may be explained by companies’ hesitancy to increase salaries beyond $1M.
|
% of Executives Receiving Salary Increases |
||||||
|
2010 – 2011 |
2011 – 2012 |
2012 – 2013 |
||||
|
No Increase |
Receiving Increase |
No Increase |
Receiving Increase |
No Increase |
Receiving Increase |
|
|
CEO |
34% |
66% |
47% |
53% |
46% |
54% |
|
CFO |
12% |
88% |
15% |
85% |
27% |
73% |
2013 Salary Increases
Actual Pay Levels
Our findings indicate that the rate of increase in total direct compensation levels for both CEOs and CFOs accelerated in 2012-2013 compared to flat pay increases in 2011-2012, supported by stronger performance in 2013. During 2012-2013, actual total direct compensation (salary plus actual annual incentive plus the grant date value of long-term incentives) for CEOs and CFOs increased by 5.2% and 3.2%, respectively. This year is the first year since 2010 that we see higher median increases in actual total direct compensation for the CEO versus the CFO. In addition to salary increases of 1-3%, annual bonuses were 4-5% higher at median and long-term incentives increased about 3% at median for both CEOs and CFOs.
Absolute CFO total direct compensation levels, on average, continue to be approximately 30% of CEO total direct compensation levels.
|
Median Percentage Change in Pay Components |
||||||
|
2010 – 2011 |
2011 – 2012 |
2012 – 2013 |
||||
|
Pay Components |
CEO |
CFO |
CEO |
CFO |
CEO |
CFO |
|
Salary |
1.8% |
3.5% |
0.5% |
3.0% |
1.4% |
3.3% |
|
Actual Bonus |
0.0% |
3.5% |
-2.8% |
-1.2% |
4.9% |
3.7% |
|
Long-Term Incentives |
10.0% |
10.3% |
0.0% |
2.0% |
3.2% |
3.3% |
|
Actual Total Direct Comp. |
3.6% |
7.5% |
-0.3% |
1.4% |
5.2% |
3.2% |
|
Financial Performance (Median Levels) |
|||
|
Year |
Total Shareholder Return (as of 12/31) |
1-Year Revenue Growth |
1-Year Net Income Growth |
|
2011 |
5% |
9% |
13% |
|
2012 |
14% |
3% |
2% |
|
2013 |
31% |
5% |
12% |
Since this was the first year financial services companies were included, we tested the results without financial services companies and found that the median increase in total direct compensation between the two data sets for CEOs and CFOs was within a 1% difference. However, total cash compensation yielded greater differences. For CFOs of non-financial services companies the median increase in total cash compensation was 1.9% vs. 4.6% median increase of the total sample. For CEOs the median increases were 3.1% vs. 4.2%, respectively. This is due to higher bonus payouts at financial services institutions in 2013.
2013 Median Salary Increase by Industry
2013 Median Actual Total Direct Compensation Increase by Industry
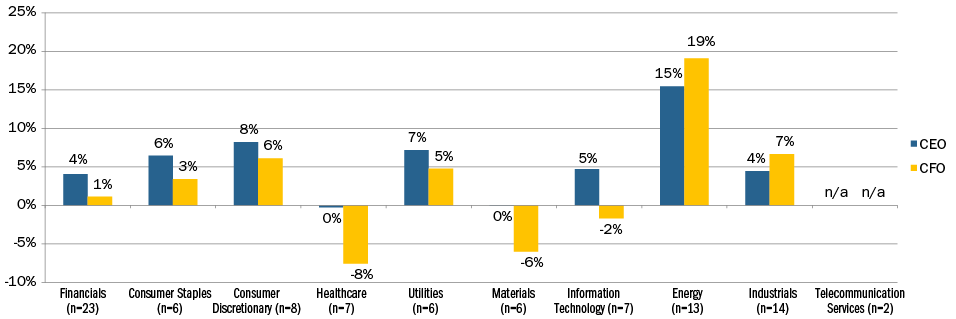
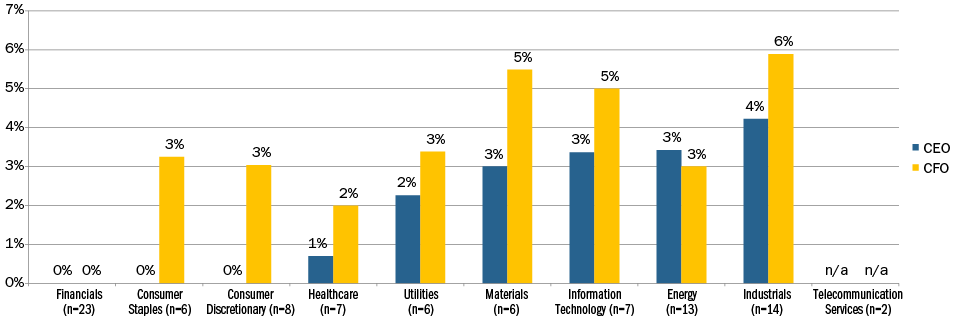
Our study breaks out 2013 CEO and CFO pay by industry classification (Financials, Consumer Staples, Consumer Discretionary, Healthcare, Utilities, Materials, Information Technology, Energy, Industrials, and Telecommunication Services). When looking at median increases in salary for both CEOs and CFOs, they tend to be in the range of 0-3%. Median salary increases over 3% occurred in the Materials and Information Technology industries for CFOs and in Industrials for both CEO and CFO. When looking at actual total direct compensation there is greater volatility in increases, which is primarily driven by industry and company performance.
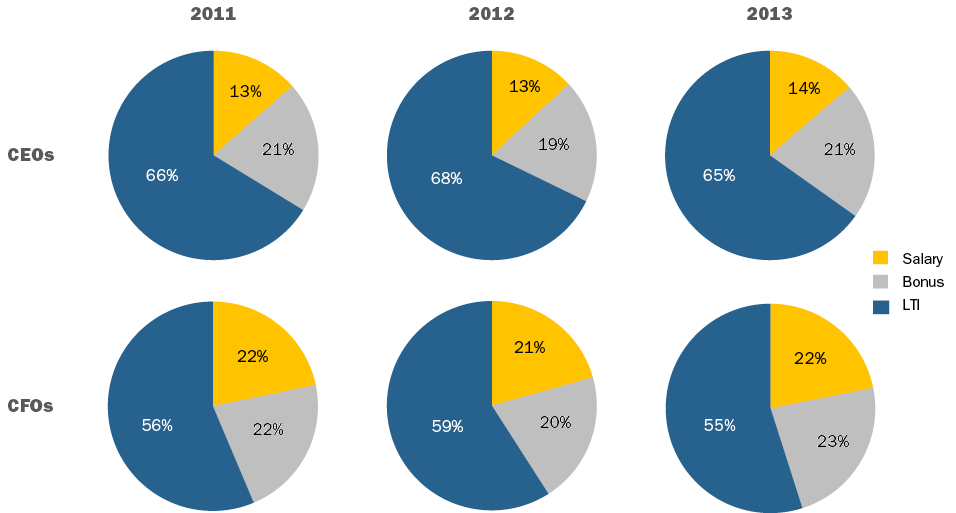
Target Pay Mix
In terms of target compensation levels, the overall pay mix remained largely unchanged from 2011 to 2013. We continue to observe a greater emphasis on at-risk pay for CEOs than for CFOs.
Long-Term Incentive (LTI) Vehicle Prevalence and Mix
LTI vehicle prevalence and mix trends have been fairly consistent over the past few years. The use of at least two long-term incentive vehicles continues to be the majority practice for CEOs and CFOs. The role of stock options has been decreasing slowly in the overall mix with companies delivering about 30% of LTI using this vehicle. On average, performance-based LTI continues to comprise approximately 50% of LTI for CEOs and CFOs. Data continues to show that about 80% of CFOs and CEOs receive some form of performance-based awards as part of their LTI program.
|
# of LTI Vehicles Used |
% in Total |
|
|
CEO |
CFO |
|
|
1 Vehicle |
25% |
27% |
|
2 Vehicles |
49% |
43% |
|
3 Vehicles |
26% |
30% |
|
Average |
2 |
2 |
|
LTI Mix |
2011 |
2012 |
2013 |
|||
|
CEO |
CFO |
CEO |
CFO |
CEO |
CFO |
|
|
Stock Options |
32% |
32% |
30% |
32% |
29% |
29% |
|
Time Vested Restricted Stock |
17% |
22% |
16% |
20% |
19% |
22% |
|
Perf. Based LTI |
51% |
46% |
53% |
48% |
53% |
49% |
Conclusion
Given the improved economy and strong stock market it is not surprising that CEO and CFO pay levels increased in 2013. The fact that CEO pay increased at a faster rate than CFOs for the first time in four years, implies that Compensation Committees are recognizing CEO performance as overall company performance improves. In the future, we expect continued pay-for-performance alignment with CEOs experiencing a greater impact on compensation for good and bad performance.