Key CAP Findings
Board Compensation. little/no change
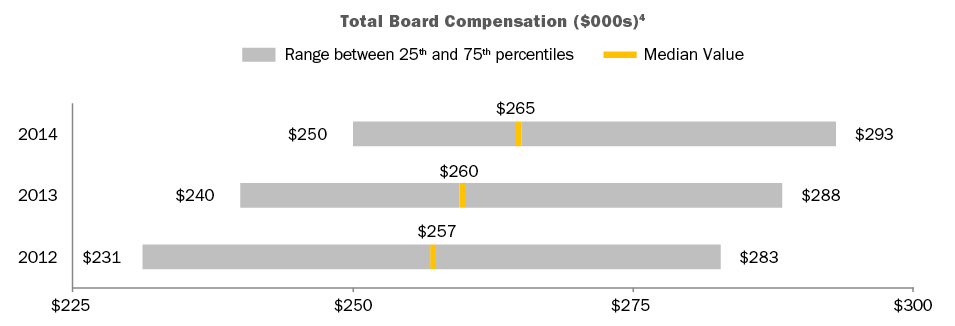
- Total Fees. Generally flat year-over-year (median is $265K, versus $260K in prior year).
- Retainers. Large companies rely on annual retainers (cash and equity) to compensate directors. Pay programs are typically simple and viewed more as an “advisory fee” than an “attendance fee.”
- Meeting fees. Provided by only 12 percent of companies (versus 15 percent in prior year). In general, companies have moved to a fixed retainer pay structure, with a component in cash and a component in equity.
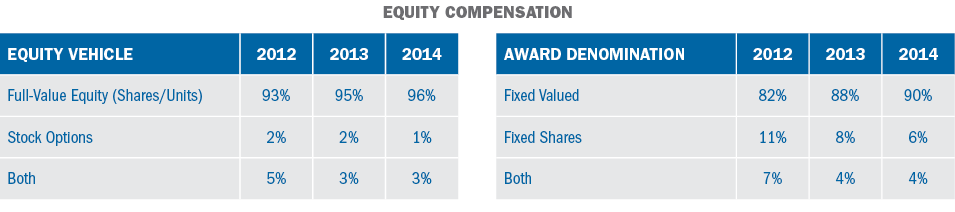
- Equity. Full-value awards (shares/units) are most common and only four percent of companies use stock options. 94 percent of companies denominate equity awards (stock or options) as a fixed value, versus a fixed number of shares which is considered best practice as it manages the value each year.
- Pay Mix. On average, 58 percent equity-based vs. 42 percent cash-based. Alignment with long-term shareholders is reinforced by delivering a majority of compensation in equity.
Committee Member Compensation. little/no change
- Overall Prevalence. 45 percent of companies paid committee-specific member fees1.
- Total Fees. Among companies paying committee member fees, the median is $15.5K.
Committee Chair Compensation. little/no change
- Overall Prevalence. Approximately 90 percent of companies provide additional compensation to committee Chairs, typically through an additional retainer, to recognize additional time requirements, responsibilities, and reputational risk.
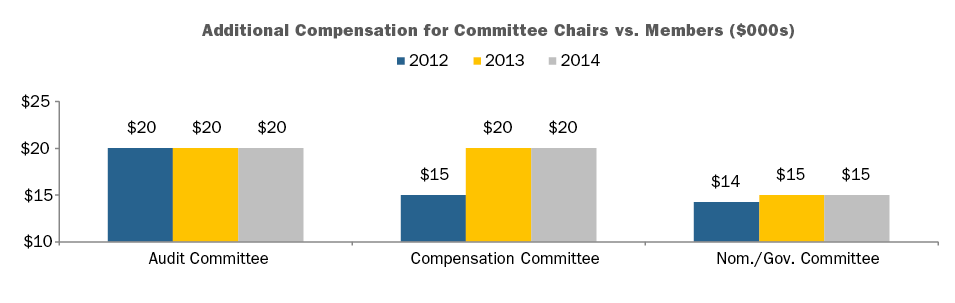
- Fees. At median, $20K in additional compensation (vs. members) was provided to Audit and Compensation Committee Chairs, and $15K additional to Nominating/Governance Committee Chairs.
Independent Board Leader Compensation. little/no change
- Non-Exec Chair. Additional compensation is provided by all companies with this role, $225K at median. As a multiple of total Board Compensation, total Board Chair pay is 1.84x a standard Board member, at median.
- Lead Director. Additional compensation – $30K, at median – is provided by nearly all companies with this role2. The differential in pay versus non-executive Chairs is in line with typical differences in responsibilities. Median additional compensation was flat – $25K – for the five years prior to 2013 (median in 2013 was $28K).
Perquisites. little/no change
- Prevalence. Overall, limited use. One-third of companies provide gift matching/charitable contribution.
Pay Limits. little/no change
- 21 percent of companies that amended or adopted new equity plans in 2015 implemented specific limits for director compensation. In total, 27 percent of Fortune 100 companies now have such limits.
CAP Perspective
Board Pay Levels and Structure
We believe director compensation has leveled off – for the time being – and expect to see only modest increases in the next year.
In terms of pay program, fixed retainer structures are now the norm and meeting fees – already minority practice – continue to decline in prevalence as director compensation is now often viewed more as an “advisory fee” than an “attendance fee.”
Director Pay Limits
A number of companies have implemented limits on director compensation. The limits are largely due to advancement of litigation in Delaware court where the issue has been that directors approve their own annual compensation, and the shareholder approved long-term incentive plan did not provide “meaningful limits” on the maximum award that could be granted to a director.
Currently, 27 percent of companies studied (vs. 23 percent in prior year) have included limits for non-employee director compensation in their shareholder approved long-term incentive plan. These limits range from $250K to $3.5 million, $770K at median (vs. $800K in prior year), and typically apply to just equity-based compensation. Some companies have applied the limits to both cash and equity-based compensation, while others have excluded initial at-election equity awards, committee Chair pay, and/or additional pay for Board leadership roles from the limit.
We expect director pay limits to become majority practice within the next few years.
Lead Director Compensation
The Lead Director role has evolved, especially in companies where the CEO and Chairman roles are combined. For example, Boards are engaging in more outreach and meeting with shareholders to talk about governance practices, CEO succession and executive compensation, among other issues, and many investors want to hear from the Lead Director. Nearly all companies studied now provide additional compensation for the Lead Director role.3 However, additional compensation provided for the Lead Director role continues to be quite different than the non-executive Chair role. At median, an additional $30K was provided for the Lead Director role, versus $225K for the non-executive Chair role. The differential in pay is generally in line with typical differences in responsibilities.
Providing additional compensation to the Lead Director sends a signal to investors regarding expectations for the role, including time commitment, responsibilities, and authority. Many times, companies have been able to settle (or argue against) shareholder proposals to split the CEO and Chairman roles by instituting (or emphasizing) a strong Lead Director role and delineating the specific responsibilities of the position. Boards can also reassure investors concerned about overall governance practices at a company by increasing Lead Director responsibilities.
Best in Class Director Compensation Process & Practices
|
Best in Class PROCESS |
|
|
Best in Class PRACTICES |
|
Appendix
1 Audit, Compensation and/or Nominating and Governance committee members.
2 Excludes controlled companies. Also excludes instances where Lead Director role is assumed by Chair of Nominating and Governance Committee, who receives compensation for that role.
3 Excludes controlled companies. Also excludes instances where Lead Director role is assumed by Chair of Nominating and Governance Committee, who receives compensation for that role
4 Total Board Compensation reflects all cash and equity compensation for Board and committee service, excluding compensation for leadership roles such as committee Chair, Lead/Presiding Director, or non-executive Board Chair.
- Perquisites represent only a small portion of the total pay program for a CEO or CFO. However, perquisite based pay is – and we expect will continue to be – highly scrutinized
- In 2014 83% of companies provided perquisites to their CEO, and 81% of companies provided perquisites to their CFO
- The four most common CEO/CFO perquisites in 2014 were: personal use of corporate aircraft, auto allowance, personal security and financial planning
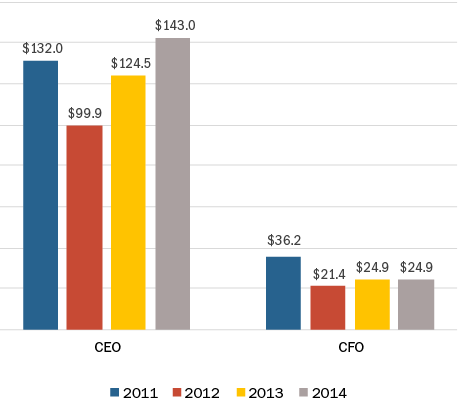
- The median value of total perquisites provided to CEOs increased by approximately 15% to $143,000 in 2014, and was flat at approximately $25,000 for CFOs
Our Survey Sample
Compensation Advisory Partners (“CAP”) reviewed 2015 proxy disclosures at a sample of 100 companies among the Fortune 500, representing nine industry groups. Industry groups included: Automotive, Consumer Goods, Financial Services, Health Care, Insurance, Manufacturing, Pharmaceutical, Retail, and Technology. For the companies studied, the median revenue size and market capitalization was $34 billion and $56 billion respectively.
What We Found
The percentage of companies in our research sample providing perquisites to their CEO stayed constant at 83% from 2013 to 2014. The percentage of companies providing perquisites to CFOs increased 5% from 2013 to 2014 to 81%.
In 2014, the four most common CEO perquisites were: personal use of corporate aircraft (56%), automobile allowance (31%), personal security (29%) and financial planning (24%). While the prevalence of personal use of corporate aircraft was generally flat from 2012 to 2014, the prevalence of automobile allowances, personal security and financial planning decreased sharply (approximately 30– 40%) over the past two years.
CEO Perquisite Prevalence
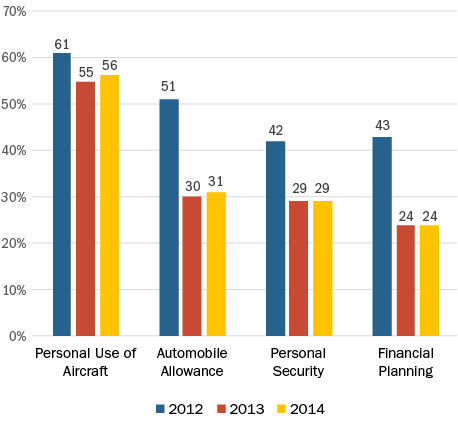
Although the prevalence of major perquisites remained steady in 2014 for CEOs compared to the prior year, the median total value for CEO perquisites increased 15% to $143,000. This value has ranged from $100,000 to $143,000 over the last four years. In contrast, the median value of perquisites for CFOs was relatively flat year-over-year, and has ranged from $21,000 to $36,000 since 2011.
Median CEO and CFO Perquisites Value ($000s)
Perquisites represent only a small portion of an executive’s total compensation, yet are often highly scrutinized. Shareholders prefer that pay be delivered in performance-based vehicles instead of through perquisites. Over the past few years, a number of companies changed their perquisite programs in reaction to increased shareholder scrutiny and specific feedback received from shareholders or proxy advisory firms. However, given fairly consistent prevalence over the past 2 years, data suggests that changes to company perquisite programs may have leveled off. PNC was the only company making a change to a perquisite program in our sample for 2014, increasing their annual perquisite limit from $10,000 to $20,000 for each NEO, other than for the CEO.
|
Perquisites Change Reported in CD&A |
2014 n=1 |
2013 n=7 |
2012 n=9 |
2011 n=14 |
||||
|
# of Cos. |
# of Cos. |
# of Cos. |
# of Cos. |
# of Cos. |
# of Cos. |
# of Cos. |
# of Cos. |
|
|
Eliminated perquisites |
0 |
0% |
6 |
75% |
2 |
22% |
9 |
56% |
|
Eliminated tax gross-ups on perquisites |
0 |
0% |
1 |
13% |
4 |
44% |
6 |
38% |
|
Reduced perquisite program/value |
0 |
0% |
1 |
13% |
2 |
22% |
1 |
6% |
|
Changed perquisite program |
1 |
100% |
0 |
0% |
1 |
11% |
0 |
0% |
Note: Percentages do not add up to 100% due to multiple changes by companies
Conclusion
While Compensation Committees continue to monitor the appropriateness (and competitiveness) of perquisite programs, as well as dollar values and overall executive usage, the degree to which executive perquisites are provided appears to have leveled off. We expect that companies will continue to closely align executive compensation with shareholder interests by limiting non-performance-based compensation, such as perquisites. We caution that any potential (perceived) misuse of executive perquisites will continue to raise the ire of shareholders and proxy advisory firms and provide for headline news.
Compensation Advisory Partners LLC (“CAP”) appreciates the opportunity to comment on proposed rules for clawbacks. As a leading executive compensation consulting firm, we support sound corporate governance.
Today, the SEC approved the final rules related to pay ratio. Companies will be required to disclose their CEO’s pay as a multiple of the pay of their median employee in their 2017 proxy (released in 2018 for calendar year filers). The SEC issued proposed rules in September 2013 and received over 280,000 comments related to the topic. For further details and thoughts please see our earlier CAPFlashes on the topic (Sept 20, 2013 and April 1, 2015) and look for more details in future CAPflashes.
Click here to read SEC’s press release on the topic.
On July 1, 2015, the SEC proposed rules directing the stock exchanges to expand listing standards to require companies to adopt clawback policies. These clawback policies would require executive officers to pay back incentive compensation that was awarded in error under an accounting restatement. According to SEC Chair Mary Jo White, the express purpose of the rules are ‘increased accountability and greater focus on the quality of financial reporting, which will benefit investors and markets.” With these proposed rules, the SEC has now addressed all of the executive compensation governance reforms included in the Dodd-Frank Wall Street Reform and Consumer Protection Act of 2010.
Where Do We Go From Here?
- Most major companies have already implemented clawback policies
- SEC proposal on clawbacks does not align with current market practice
- Includes current and former executive officers
- Triggered exclusively by an accounting restatement resulting from an error
- Triggered regardless of whether executive has committed fraud or misconduct related to the accounting restatement
- Includes a 3-year look-back period
- Generally precludes board discretion
- Accompanied by onerous disclosure rules
- Assess your company’s current clawback policy against the proposed rules
- Brief senior management and the board on the scope of the proposed rules
- Await further developments after the public comment period ends and final rules are issued
Broad Scope
The SEC’s proposal amends the Securities Exchange Act of 1934 (the “Exchange Act”) by adding new Exchange Act Rule 10-D1. Other amendments would apply to filings by foreign private issuers and certain investment companies. As a result, the clawback rules will apply to virtually all listed issuers of equity securities, debt and preferred securities, including emerging growth companies, smaller reporting companies, foreign private issuers and controlled companies.
New Rule 10-D1
As proposed, an issuer would be subject to delisting if it fails to (1) adopt a clawback policy that complies with the new requirements, (2) disclose the policy and (3) comply with the policy to recover compensation under an accounting restatement. Under the proposal, clawback of incentive compensation would be required from current and former executive officers who received excess incentives during the three fiscal years prior to the date on which a company is required to prepare an accounting restatement to correct a material error. The clawback provision applies on a “no fault” basis, regardless of whether misconduct occurred and regardless of whether an individual had any responsibility for the error.
The amount subject to clawback would be the amount that exceeds the amount that the executive officer would have received if the incentive compensation had been determined using restated financial statements. The proposed rules direct companies to use reasonable estimates of the effect that an accounting restatement would have on stock price and total shareholder return to determine amounts subject to recovery.
Limits on Board Discretion
Under the proposal, the situations where a Board could elect not to pursue recovery are limited. The SEC specified situations where the direct expense related to enforcing recovery would exceed the amount recovered. However, even in these situations, the Board would have to go through the process of determining the amount subject to clawback and make an attempt at recovery before deciding not pursue enforcement of the recovery. In addition, foreign private issuers could elect not to comply when clawback would violate home country law.
Trigger for Recovery
New Rule 10-D1 would trigger a clawback in the event that the issuer prepares a restatement of previously issued financial statements to correct an error that was material. Note that the requirement to restate financial statements is enough to trigger the clawback provisions, allowing the SEC to avoid the potentially thorny question of what constitutes a material error. Under GAAP, an error may include mathematical mistakes, mistakes in the application of GAAP principles, or oversights or misuse of facts when the financial statements were prepared. The proposal indicates several types of changes to financial statement that are not error corrections and would not trigger clawback, including
- Retrospective application of a change in accounting principle;
- Retrospective revision to reportable segment information due to a change in the structure of the issuer’s organization;
- Retrospective reclassification due to a discontinued operation;
- Retrospective application of change in reporting entity, such as from a reorganization;
- Retrospective adjustment to provisional amounts in connection with a prior business combination; and
- Retrospective revision for stock splits.
3-Year Look-Back Period
The proposed clawback will apply to excess incentives during a 3-year period prior to the date on which the issuer is required to prepare an accounting restatement. The proposal defines this date as the earlier of:
- The date the issuer’s board of directors, a committee of the board of directors, or the officer or officers of the issuer authorized to take such action if board action is not required, concludes , or reasonably should have concluded , that the issuer’s previously issued financial statements contain a material error; or
- The date a court, regulator or other legally authorized body directs the issuer to restate its previously issued financial statements to correct a material error.
The SEC notes that the first proposed date would generally coincide with the filing of Form 8-K, but Form 8-K is not necessary for recovery. Further, the obligation to clawback does not depend on whether or when restated financial statements are filed.
Application to Executive Officers
The proposed clawback rules apply to current or former executive officers who received incentive compensation. Under the proposal, executive officer is defined as the issuer’s president, principal financial officer, principal accounting officer (or controller), any vice president to the issuer in charge of a principal business unit, division or function (such as sales, administration or finance), any other officer who performs a policy-making function, or any other person who performs a similar policy-making functions for the issuer.
This proposed definition of executive officer is modeled on the definition used in Section 16, so it will apply to a reasonably large group of senior executives. The proposal also specifies that individuals who served as an executive officer at any time during the performance period for incentive compensation subject to recovery will be subject to clawback. This would include incentive compensation authorized before the individual becomes an executive officer and inducement awards granted in new hire situations.
Compensation Subject to Clawback
The SEC proposal contains a very broad definition of “incentive-based compensation” subject to clawback. As proposed, this would be defined as “any compensation that is granted, earned or vested based wholly or in part upon the attainment of any financial reporting measure.” The rules would also specify that “financial reporting measures” are measures determined and presented in accordance with the accounting principles used to prepare the issuer’s financial statements, any measures derived wholly or in part from such financial information and stock price and total shareholder return.
This definition wraps in accounting-based measures, as well as non-GAAP measures. Notably the SEC proposal includes stock price and total shareholder return. Although these are not accounting-based measures, the SEC included them because these measures are affected by accounting information and subject to current disclosure (i.e., stock performance graph and disclosure of high and low stock prices for each quarter within the two most recent fiscal year and any subsequent interim periods). Importantly, stock options and restricted stock that vest solely based on continued service are not subject to clawback.
The SEC acknowledges the complexities associated with trying to determine the amount of excess compensation related to the relationship between an accounting error and stock price. The SEC recognizes that complex analyses may be required. As a solution, the SEC suggests that issuers be permitted to make reasonable estimates and requires disclosure of these estimates.
The proposal includes examples of compensation that would be subject to clawback, as well as compensation that would be excluded:
|
Compensation Subject to Clawback |
Compensation Excluded from Clawback |
|
Non-equity incentive plan awards that are earned based wholly or in part on satisfying a financial reporting measure performance goal |
Salaries |
|
Bonuses paid from a bonus pool, the size of which is determined based wholly or in part on satisfying a financial reporting measure performance goal |
Bonuses paid solely at the discretion of the Compensation Committee or Board, not paid from a pool determined wholly or in part on satisfying a financial reporting measure goal |
|
Restricted stock, RSUs, performance shares, stock options and SARS that are granted or become vested wholly or in part on satisfying a financial reporting measure performance goals |
Bonuses paid on subjective standards (e.g., leadership) and/or completion of a specified employment period |
|
Proceeds received upon the sale of shares acquired through an incentive plan that were granted of vested based wholly or in part on satisfying a financial reporting measure performance goal |
Non-equity incentive plan awards earned solely upon satisfying one or more strategic measures (e.g., consummating a merger or divestiture) or operational measures (e.g., opening a specified number of stores, completion of a project, increase in market share) |
|
Equity awards for which the grant is not contingent upon achieving any financial reporting measure performance goal and vesting is contingent solely upon completion of a specified employment period and/or attaining one or more non-financial reporting measures |
Proposed Disclosure Requirements
Proposed new Rule 10D-1 would require disclosure of the issuer’s policy related to clawback of erroneously awarded compensation. The clawback policy would need to be filed as an exhibit to Form 10-K for listed U.S. issuers.
The proposal contains additional disclosure requirements that are extensive when a restatement was completed or an outstanding balance of excess incentive-based compensation relating to a prior restatement. In these instances, the proposed disclosure would include:
- For each restatement, the date on which the listed issuer was required to prepare an accounting restatement, the aggregate amount of excess incentives and the aggregate amount that remains outstanding as the end of the most recent completed fiscal year;
- The estimates used to determine the excess incentive compensation related to a stock price or total shareholder return measure;
- The name of each person subject to clawback for whom the listed issuer decided not to pursue recovery, the amount forgone and a description of the reason the issuer decided not to pursue recovery; and
- The name and amount due from each person from who, at the end of the last completed fiscal year, excess incentive-based compensation had been outstanding for 180 days or longer.
The proposed disclosure would be included as a separate item, not part of the CD&A. However, companies would have the option of providing the information in the CD&A to provide all information related to the clawback policy in one place.
The proposed rules also include amendments to Summary Compensation Table disclosure. Amounts previously reported would be reduced by the amount recovered by clawback with a footnote explanation. Finally, the required disclosure would be provided as interactive using XBRL block-text tagging.
Other Important Provisions
The proposed rules are incorporated in a 198 page filing. They are very detailed and complex. This article necessarily serves as a summary of the most important points that we see as being of general interest. But there are other details that shed light on the SEC’s thinking, as follows:
- Incentive-based compensation recovery will apply to pre-tax amounts.
- Clawback may occur simultaneously under new Rule 10D-1 and SOX Section 304. If an individual reimburses the Company under Section 304, a credit will be recorded for purposes of new Rule 10D-1.
- Lack of compliance with a clawback policy threatens a company with delisting, depending on the stock exchange’s assessment of whether the company was making a good faith effort to clawback compensation.
- Companies may not indemnify executive officers or former executive officers against the loss of erroneously awarded compensation.
- If an executive purchases third-party insurance, companies would be prohibited from paying the premiums for this insurance.
Timing of New Rules
The SEC’s proposal calls for prompt implementation. The current comment period extends for 60 days. After final rules are adopted, the SEC is calling for the stock exchanges to file their proposed amended listing standards within 90 days. Following the effective date of the stock exchange listing standards, each listed company would be required to adopt a clawback policy within 60 days. Clawback would apply to all excess incentive-based compensation received for any fiscal year ending on or after the effective date of new Rule 10D-1. Similarly, disclosure requirements would become effective immediately on or after the date on which the stock exchange listing standards become effective.
Annually, Compensation Advisory Partners (CAP) evaluates pay levels for Chief Financial Officers (CFOs) and Chief Executive Officers (CEOs). This year’s analysis is based on a sample of 108 companies with median revenues of $12.4 billion. For more information on how we developed the sample of companies, please see below under Sample Screening Methodology.
Highlights
- Salary increases were provided much more frequently to CFOs, with approximately 70% receiving a salary increase, than to CEOs
- The median salary increase was only 0.3% for CEOs, while CFO salaries grew by 3.0%
- Similar to last year, the median increases in actual total direct compensation (i.e., cash plus equity) for both CEOs and CFOs, were in the low single-digits
- 2014 median increases in actual total direct compensation were 3.2% for CEOs and 5.2% for CFOs
- Slightly higher pay growth for CFOs was partially driven by higher annual bonus target opportunities in 2014
- On an absolute basis, CFO total compensation continues to approximate one-third of CEO total compensation
- Little or no changes observed in how long-term incentives are delivered to CEOs and CFOs; Long-term incentive mix continues to emphasize performance-based equity
Study Results
Salaries
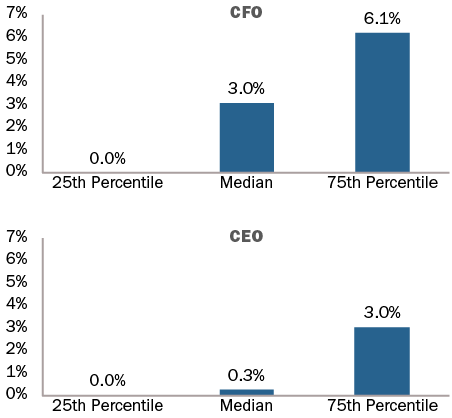
In the last 2 years, approximately 70% of CFOs received salary increases. The median salary increase for CFOs was 3.0% and the 75th percentile salary increase was 6.1%. In comparison, only about half of CEOs received salary increases. The median salary increase for CEOs was only 0.3% at median and the 75th percentile salary increase was 3.0%.
|
% of Executives Receiving Salary Increases |
||||
|
|
2012 – 2013 |
2013 – 2014 |
||
|
|
No Increase |
Receiving Increase |
No Increase |
Receiving Increase |
|
CEO |
52% |
48% |
49% |
51% |
|
CFO |
31% |
69% |
28% |
72% |
2014 Salary Increases
Actual Pay Levels
Our findings indicate a median rate of increase in actual total direct compensation levels for both CEOs and CFOs in the low-single digits. The median increases over the last two years ranged between 3% and 5%. During 2013-2014, actual total direct compensation (salary plus actual annual incentive plus the grant date value of long-term incentives) for CEOs and CFOs increased by 3.2% and 5.2%, respectively.
Industry Trends
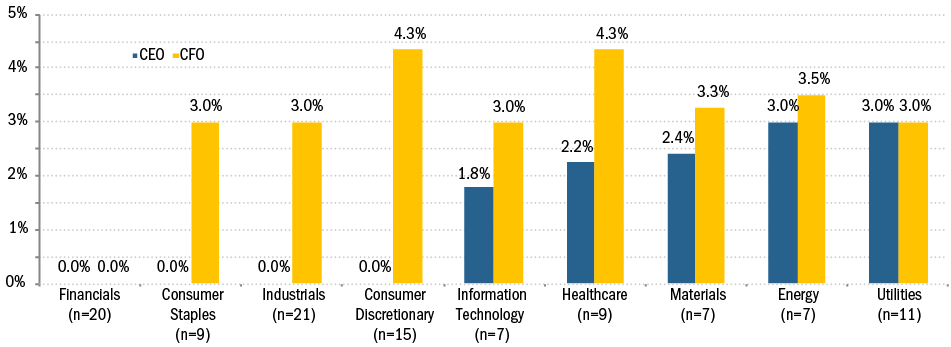
2014 Median Salary Increase by Industry
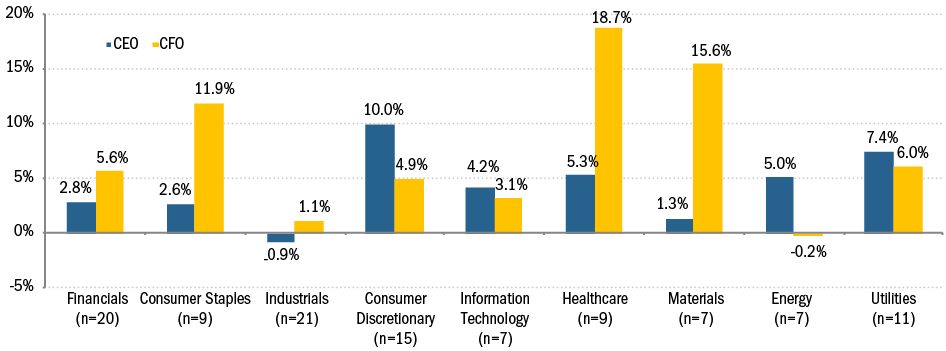
2014 Median Actual Total Compensation Increase by Industry
|
Median Percentage Change in Pay Components |
||||
|
|
2012 – 2013 |
2013 – 2014 |
||
|
Pay Components |
CEO |
CFO |
CEO |
CFO |
|
Salary |
0% |
3.0% |
0.3% |
3.0% |
|
Actual Bonus |
4.1% |
3.7% |
4.3% |
7.8% |
|
Long-Term Incentives |
2.3% |
3.1% |
3.7% |
4.2% |
|
Actual Total Direct Compensation |
3.7% |
3.6% |
3.2% |
5.2% |
As seen in the table above, the median 2014 increase in actual bonus for CFOs was double the median increase for CEOs. This large increase in annual bonus is partially driven by higher bonus target opportunities in 2014 for CFOs, with the median target bonus increasing from 90% to 100% of salary. In contrast, CEO target bonus opportunities remained relatively flat at approximately 150% of salary.
|
Target Bonus as % of Salary |
||||
|
|
2013 |
2014 |
||
|
Pay Components |
CEO |
CFO |
CEO |
CFO |
|
25th Percentile |
125% |
75% |
125% |
80% |
|
Median |
147% |
90% |
150% |
100% |
|
75th Percentile |
170% |
100% |
165% |
105% |
When analyzed by industry, median increases in salary for CEOs are generally less than 3%. Median salary increases to CFOs are much more robust, generally in the range of 3-4%. Median salary increases over 3% are seen for CFOs in the following industries: Consumer Discretionary, Energy, Healthcare, and Materials. The Financials industry is the only industry were the median change in salary was 0% for both CEOs and CFOs.
When we look at actual total direct compensation by industry, greater volatility is observed. The volatility in year-over-year changes is primarily driven by industry and company performance. Some of the largest increases in compensation levels are seen in Consumer Staples, Healthcare and Materials.
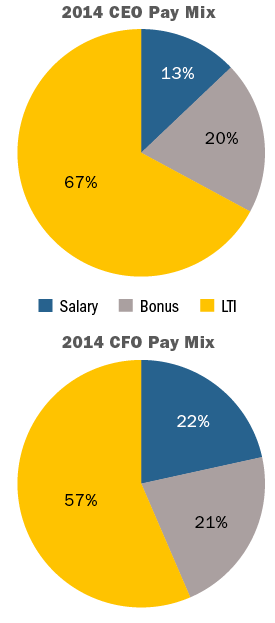
Target Pay Mix
The average total target compensation pay mix remained largely unchanged. At-risk pay continues to be more emphasized for CEOs than for CFOs.
Long-Term Incentive (LTI) Vehicle Prevalence and Mix
Equity mix and vehicles used for LTI awards remained fairly consistent for the past several years. The majority of companies continue to use two different vehicles to deliver long-term incentives to CEOs/CFOs and a quarter of companies studied use all three equity vehicles (time-based stock awards, awards under a performance plan, and stock options)
Performance plans account for roughly 50% of LTI awards, about 25% is delievered in stock options, and about 25% in time-vested restricted stock awards. The overall percentage of performance-based awards (performance plans and stock options) for both CEOs and CFOs continues to range between 75% – 80%.
|
LTI Mix |
||||
|
|
2013 |
2014 |
||
|
|
CEO |
CFO |
CEO |
CFO |
|
Stock Options |
27% |
27% |
26% |
25% |
|
Time Vested Restricted Stock |
17% |
22% |
21% |
26% |
|
Performance Plans |
56% |
51% |
53% |
49% |
Conclusion
In terms of performance, 2014 was a good year for our sample of companies with median total shareholder return of 15%, median revenue growth of 5% and median net income growth of 9%. We believe the 2014 pay changes were aligned with performance for the year. For CEOs, salary increases were modest, but increases in actual bonus and long-term incentives contributed to a median increase in actual total direct compensation of 3.2%. Pay progression opportunities for CFOs were even stronger, with a median increase of 7.8% in actual bonus and 4.2% in long-term incentives yielding a 5.2% median increase in actual total direct compensation.
In terms of compensation program design for senior executives, we saw relatively little change. The increase in annual target bonus opportunity for CFOs was noteworthy, but long-term incentives practices are similar to last year’s study. The increase in performance-based long-term incentives is significant and we expect this to remain the mainstream practice.
Sample Screening Methodology
Based on the screening criteria below, we arrived at a sample of 108 public companies with median 2014 revenue of $12.4B.
|
Revenue |
At least $5B in revenue for fiscal year 2014 |
|
Fiscal year-end |
Fiscal year-end between 9/1/2014 and 12/31/2014 |
|
Proxy Statement Filing Date |
Proxy statement filed before 3/31/2015 |
|
Tenure |
No change in CEO and CFO incumbents in the past three years |
|
Industry |
All industries have been considered for this analysis |
Proposed amendments to Item 402 of Regulation S-K outline additional disclosure requirements designed to implement Section 14(i) of the Securities Exchange Act of 1934 (the “Exchange Act”), as added by Section 953(a) of the Dodd-Frank Wall Street Reform and Consumer Protection Act (“Dodd-Frank”).