Beginning with fiscal years ending on or after December 31, 2017, companies are required to disclose the ratio that compares the compensation of the CEO to the compensation of the median employee (pay ratio). This disclosure was part of the Dodd-Frank Wall Street Reform and Consumer Protection Act signed into law in 2010.
Compensation Advisory Partners LLC (CAP) researched early pay ratio disclosures. As of March 9, 2018, we obtained pay ratios from 150 companies with a median revenue of $2.1B from a cross-section of industries.
Pay Ratio
The median pay ratio disclosed by these companies is 87x. The lowest ratio is 1x (Apollo Global Management, Dorchester Minerals and The Carlyle Group) and the highest ratio is 1465x (Fresh Del Monte Produce Inc.).
| Summary Statistics | Median Employee Pay | Median CEO Pay | Pay Ratio |
| 75th percentile | $88,612 | $10.5M | 172x |
| Median | $58,256 | $5.6M | 87x |
| 25th percentile | $43,966 | $2.5M | 36x |
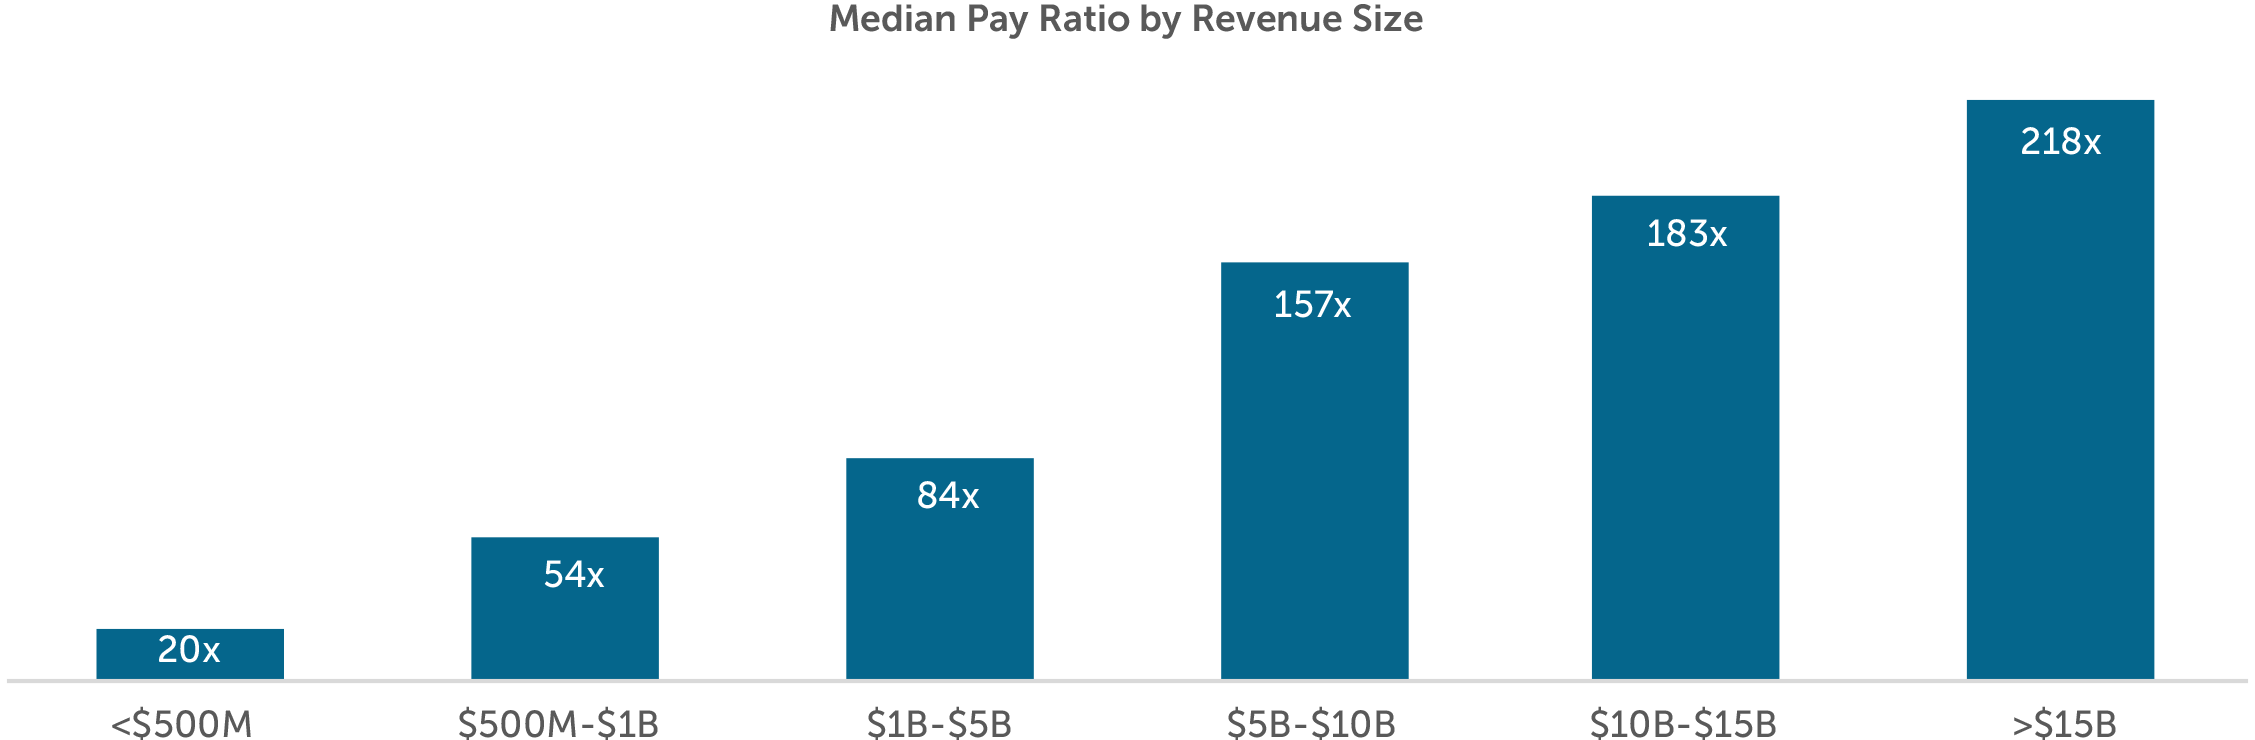
As expected, the pay ratio correlates with company size, with larger companies disclosing higher ratios. CEO pay varies greatly depending on the size and complexity of the organization. Employee pay has less variability since it reflects the job function and does not vary significantly based on the size of the organization. The median ratio in our sample of 150 companies ranges from 20x for companies with revenue less than $500M to 218x for companies with revenue greater than $15B.
Few companies, 15, disclose a supplemental pay ratio with only a handful of companies (three) disclosing more than one additional ratio. These companies with supplemental ratios are typically adjusting the CEO’s pay which may exclude anomalies such as a one-time special bonus or equity award. Interestingly, three companies disclosed a higher supplemental pay ratio likely to provide context for a large year over year increase in the 2019 proxy statement.
Location of Disclosure
Nearly 70% of companies disclose the pay ratio after the Potential Payments upon Termination or Change in Control section of the proxy statement. Approximately 25% of companies disclose the pay ratio just before or after the Summary Compensation Table and a small minority, 5%, disclose it in the Compensation Discussion and Analysis (CD&A).
Pay ratio is typically not disclosed in the CD&A, signaling to shareholders that the pay ratio is not used to determine CEO pay levels. Additionally, around 25% of companies include language in the disclosure that the ratio should not be used to compare pay levels to other companies within the industry, region of the country or revenue size.
Measurement Date
The SEC’s final rules give companies the flexibility to use any date within the last quarter of the fiscal year to identify the median employee. Companies most commonly used the last day of the fiscal year or a date within the last month of Q4. It is also common for companies to use a day within the first month of Q4 to identify the median employee.
| Measurement Month | Prevalence | Measurement Date | Prevalence | |
| First Month of Q4 | 29% | Last day of Q4 | 44% | |
| Second Month of Q4 | 8% | First day of Q4 | 17% | |
| Third Month of Q4 | 57% | Other | 33% | |
| Not Disclosed | 6% | Not Disclosed | 6% |
Exclusions from Median Employee Determination
Approximately one-third of companies excluded a portion of their workforce when determining the median employee. The most common rationale is the de minimis exemption (approximately 55%) whereby a company can exclude up to 5% of its non-U.S. employee workforce. Companies also commonly cited an acquisition or corporate not responsible for setting pay (e.g., independent contractors) as rationales for excluding certain employee groups.
Conclusion
As more companies continue to file their proxy statements in the coming weeks, we will likely see larger pay ratios, particularly as companies with a significant part-time workforce begin to disclose their ratios. We do not anticipate an increasing trend in the number of companies filing supplemental pay ratios though it will be interesting to see the rationale for those that do. We expect to continue to see companies placing the pay ratio outside of the CD&A with most disclosing it after the Potential Payments upon Termination or Change in Control section.
On a panel of leading executive compensation experts, Margaret Engel discusses some of the top executive compensation issues and trends including: the current public mistrust of executive compensation programs, the importance and the rigorous process of target goal setting, the challenges that many companies face with long-term performance awards, and the likely increase in the use of performance-based stock options in the future.
Setting goals for long-term incentives has been a persistent problem for companies and Compensation Committees ever since the reliance on long-term performance plans has increased. However, the results of the recent election take the uncertainty to an entirely new level, right around the time when companies are starting to think about setting goals for their upcoming long-term incentive cycle. Examples of challenges various industries will face include:
Energy & Utilities
- Volatility of energy prices given the views on natural gas and oil
- Environmental regulations (i.e. carbon dioxide emissions)
- Traditional sources of energy vs. renewables
Financial Services
- Dodd-Frank implications
- Movement in interest rates
- Return of Glass-Steagall
Industrial and Materials Companies
- Investment in large infrastructure projects
- Renegotiation of trade deals and increased tariffs on goods
None of the above even touches on the implications for businesses if the administration implements a broad-reaching immigration initiative which can have implications on labor costs or if President-elect Donald Trump is successful at dramatically lowering the corporate tax rate.
In many ways, it is similar to the level of uncertainty companies and Boards were dealing with during and immediately following the financial crisis. As Compensation Committees and management plan for 2017 and beyond, a challenge will be setting goals in a company’s 1- and 3-year incentive plans. As such, Compensation Advisory Partners (“CAP”) outlines four things to think about when setting goals to avoid unintended outcomes and maximize flexibility and accountability.
- Scenario Testing – Run scenarios to test sensitivities and potential outcomes. For example, test what will happen if energy prices go up/down/stay flat and what will happen to payouts under the varying scenarios. Discuss this analysis with the Compensation Committee and establish guiding principles for what is a reasonable payout under the varying scenarios.
- Retrospective analysis – Over periods of uncertainty, companies can meet or miss their goals for many reasons. If the next four years are as volatile as currently expected, Compensation Committees should encourage management to do a retrospective analysis at the end of each performance cycle comparing actual performance to expected performance when goals were set. For example, if the company ultimately delivers $3.00 EPS and the goal was $2.50, did the company get there through true outperformance, because of changes in non-controllable events or because corporate tax rates declined? This retrospective analysis can help guide the Compensation Committee in determining how challenging the goals wound up being and if appropriate, make necessary adjustments to payouts.
- Wider range – As the ability to predict the future diminishes, it can often be helpful to rethink the range around target that justifies a threshold and maximum payout. For example, if a company has a high level of confidence in the ability to achieve planned performance, then they might set a relatively narrow range around target (e.g., 95% of plan for threshold and 105% of plan for maximum). However, if the company has less confidence in the ability to set its plan, a wider range (e.g., 90% of plan for threshold and 110% of plan for maximum) may be more appropriate such that deviation from plan does not have as much as much of an impact on payouts.
- 162m Umbrella Plan – With significant uncertainty it may be challenging to predict what, if any, adjustments a Compensation Committee may want to make to their annual or long-term performance plan. This would be a good time to consider implementing, if you have not already, a 162m umbrella plan to provide the Compensation Committee with flexibility to make adjustments and maintain tax deductibility. An umbrella plan is a structure whereby a bonus is effectively “over-funded” for the Named Executive Officers (“NEOs”) such that the Compensation Committee can determine the final payout with some flexibility as long as the final payout is below the umbrella funded amount. For example, in order to qualify as performance-based compensation, a company could establish a maximum to be paid equal to 3% of net income and specify a percentage of the award pool for the each NEO (excluding the CFO). The Compensation Committee then retains negative discretion to pay less than the maximums established. These umbrella plans are very common for annual incentives, but are less common for long-term plans, though this might be a good time to consider whether one might be appropriate.
There are many other ways of addressing uncertainty around goal setting, but these four tips should help maintain a pay for performance structure, hold management accountable and provide Compensation Committees with appropriate flexibility.
Today, Institutional Shareholder Services (ISS) announced a methodology update to its CEO pay-for-performance assessment for U.S. companies. Beginning February 1, 2017, ISS proxy research reports will include a new standardized comparison of a company’s financial performance relative to its ISS-defined peer group.
This is a departure from ISS’ sole reliance on Total Shareholder Return (TSR) as a metric. ISS will measure multiple financial metrics which may include Return on Equity, Return on Assets, Return on Invested Capital, Revenue growth, EBITDA growth and Cash Flow (from Operations) growth; these metrics will supplement TSR, but only in the qualitative assessment. ISS will calculate a weighted average of select financial metrics; measures (and weightings) will be based on a company’s four-digit GICS industry group. For 2017, the new financial assessment will not be included in the quantitative assessment although ISS may incorporate a company’s relative financial performance in its qualitative discussion.
This is a significant change to ISS’ pay-for-performance methodology which primarily assesses performance based on Relative TSR. While the additional financial metrics will not be included in the quantitative assessment for the 2017 proxy season, it can provide shareholders with additional context of a company’s overall financial performance. The implication is that TSR will still drive a company’s specific level of concern in the quantitative tests. However, if the company’s financial metrics are not aligned with their stock performance, it could weigh heavily on whether they receive a “For” or an “Against” recommendation from ISS on the Say on Pay vote. Examples where this new policy could help a company is if the market has overreacted to news or industry shifts, but the underlying financials are still relatively strong. When ISS releases the details on the definition and weightings of each financial metric, it will be important for a company to model the financial performance relative to the ISS-defined peer group to understand how its performance will be viewed relative to comparators.
With this updated methodology, however, realizable pay will become increasingly more important in a company’s overall pay-for-performance assessment. By taking a more holistic look at stock and financial performance, ISS may more appropriately capture the linkage between actual compensation earned and the underlying financial performance.
Additionally, ISS has historically relied on S&P to provide financial data, which does an effective job at creating comparability across companies financials. However, they are typically limited in the adjustments they can make across companies (ISS will likely use GAAP definitions, where applicable) and, therefore, a company’s view of its relative performance (which may include adjustments) could differ from ISS. This could be true where there are significant differences between a company’s peer group and the ISS peer group, particularly for companies with a cross-industry peer group (which are more commonly used with large cap companies).
In addition to incorporating financial performance metrics, ISS also announced that it will no longer include companies with less than two years of TSR and pay data in the Relative Degree of Alignment (RDA) assessment. This change will only impact newly public companies.
Overall Findings
- Performance: 2015 performance (based on Revenue growth, Pre-tax Income growth, EPS growth and 1-year Total Shareholder Return or TSR) was weaker than 2014 performance.
- CEO Pay: Median CEO pay was up 13% from 2014, driven by significant increases in the grant date value of long-term incentives (LTI) which are typically granted during the beginning of the fiscal year.
- Annual Incentive Payout: At median, annual incentive payouts (as a percentage of target) were lower in 2015 than the prior year. Additionally, there was more variability in payout around target compared to 2014 demonstrating a directional alignment between pay and performance.
- LTI Payout: Performance share plans paid out at target for the 2013-2015 performance period despite strong median 3-year cumulative TSR performance of 56%.
- Disclosure: Companies generally did not make wholesale changes to their proxy statements. Some enhanced their disclosure through the use of charts and graphs to make the proxy statement a communications document for shareholders.
2015 PERFORMANCE
2015 was a year that included an increase in the value of the U.S. dollar, volatility in foreign currency exchange rates and a slowdown in economic growth overseas (particularly in China). These factors contributed to 2015 performance being weaker than 2014 performance. CAP reviewed Revenue growth, Pre-tax Income growth, EPS growth and TSR performance for the Early Filers and the S&P 500. For the measures reviewed, 2015 performance was generally flat (0 – 3% growth) compared to the strong performance of 2014.
|
Financial Metric |
2014 Median 1-year Performance |
2015 Median 1-year Performance |
||
|
S&P 500 |
Early Filers |
S&P 500 |
Early Filers |
|
|
Revenue Growth |
5.6% |
5.7% |
0.8% |
2.4% |
|
Pre-Tax Income Growth |
8.6% |
6.4% |
0.2% |
1.2% |
|
EPS Growth |
10.6% |
10.4% |
2.6% |
3.2% |
|
TSR (1) |
16.3% |
14.1% |
2.3% |
0.3% |
(1) TSR for the S&P 500 is as of September 30, 2014 and September 30, 2015. TSR for Early Filers is as of each company’s fiscal year end.
CEO TOTAL DIRECT COMPENSATION
Among Early Filers with CEOs in their role for at least two years (n=42), 2015 actual total direct compensation increased 13% over 2014 pay levels. 2015 annual incentive payouts were down 3% reflecting weaker financial performance compared to the prior year. LTI grants in 2015, however, were significantly higher than 2014. This finding is likely reflective of the timing of LTI grants (typically in the first quarter of the fiscal year) and companies likely providing larger grants in 2015 because of the strong performance in 2014. Consistent with the expected salary increases, 2015 base salary was 3% higher than 2014.
|
Compensation Element (n=42) |
2014 Median ($000) |
2015 Median ($000) |
% Increase |
|
Base Salary |
$1,000 |
$1,031 |
3.1% |
|
Actual Annual Incentive |
$1,791 |
$1,731 |
-3.4% |
|
Total Cash |
$2,836 |
$2,663 |
-6.1% |
|
Long-Term Incentive (LTI) |
$5,468 |
$6,896 |
26.1% |
|
Total Direct Compensation |
$8,290 |
$9,399 |
13.4% |
INCENTIVE COMPENSATION
Annual Incentive Plan Payout
As mentioned above, actual annual incentive payouts in 2015 were lower than 2014. At median, 2015 payouts were 101% of target vs. 2014 payouts which were 111% of target. At the 25th percentile, 2015 payouts were much lower (76%) than 2014 (99%) but were more in line with 2013 and 2012 payouts which is indicative of a return to more normalized distribution of payouts in 2015.
|
Summary Statistics |
Annual Incentive Payout as a % of Target |
|||
|
2012 |
2013 |
2014 |
2015 |
|
|
75th Percentile |
130% |
127% |
135% |
133% |
|
Median |
100% |
95% |
111% |
101% |
|
25th Percentile |
72% |
75% |
99% |
76% |
As expected, performance was noticeably stronger for companies with an annual incentive payout that was at or above target. Conversely, performance for companies with a payout below target was weaker in 2015. These results are similar to 2014 performance, although TSR was stronger for companies with below target payout in 2014 (+7%) compared to 2015 (-11%).
|
Financial Metric |
2014 Median 1-year Performance |
2015 Median 1-year Performance (1) |
||
|
Below target payout (n=15) |
At or above target payout (n=35) |
Below target payout (n=24) |
At or above target payout (n=24) |
|
|
Revenue Growth |
3.6% |
6.3% |
-4.0% |
7.0% |
|
Pre-Tax Income Growth |
-2.9% |
12.7% |
-7.2% |
11.7% |
|
EPS Growth |
-3.4% |
13.5% |
-2.9% |
13.9% |
|
TSR (2) |
7.2% |
16.0% |
-10.7% |
12.6% |
(1) Excludes 2 companies that had spin-offs during 2015.
(2) TSR for Early Filers is as of each company’s fiscal year end.
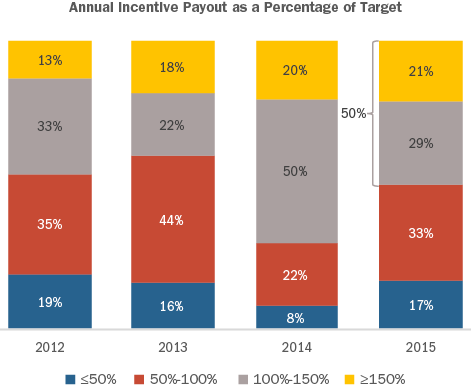
Overall, 50% of companies provided a payout at or above target in 2015 (consistent with 2013 and 2012) which is much lower than 2014 (70% of companies); as a result, there was more variability in payouts relative to target in 2015 than in 2014. Additionally, the number of companies providing a payout between 100 – 150% of target in 2015 is approximately half of what it was in 2014. Interestingly, nearly the same number of companies provided a payout of 150% and above in both 2014 and 2015. Finally, the number of companies not providing an annual incentive payout in 2015 increased (4 companies in 2015 vs. 1 company in 2014).
Long-Term Incentive Plan Payout
Three-year (2013 – 2015) performance was strong among Early Filers and the S&P 500. Cumulative Revenue growth was 11% (or 4% per year) for both Early Filers and the S&P 500. Cumulative EPS growth was very strong (21%) for the S&P 500 and more modest (11%) for the Early Filers. Overall, companies in both groups had significant stock price appreciation over the three-year period; 3-year cumulative TSR was 48% for the S&P 500 and 56% for the Early Filers.
|
Financial Metric |
Median 3-year Cumulative Performance |
|
|
S&P 500 |
All Early Filers (1) (n=42) |
|
|
Revenue Growth |
10.9% |
11.0% |
|
Pre-Tax Income Growth |
15.6% |
12.1% |
|
EPS Growth |
21.3% |
10.9% |
|
TSR (2) |
48.0% |
55.7% |
(1) Reflects only those companies with a performance share plan.
(2) TSR for the S&P 500 is as of September 30, 2015. TSR for Early Filers is as of each company’s fiscal year end.
Despite strong TSR performance over the three-year period, and even with 60% of companies using Relative TSR as a performance metric, median LTI payout was around target (98%). Median LTI payout for companies that use Relative TSR was slightly below target (95%); however, a majority of these companies (60%) use TSR in conjunction with other financial metrics.
|
Summary Statistics |
LTI Payout as a % of Target |
|
|
All Early Filers (n=42) |
Early Filers with TSR as a Metric (n=26) |
|
|
75th Percentile |
128% |
119% |
|
Median |
98% |
95% |
|
25th Percentile |
54% |
54% |
PROXY STATEMENT DISCLOSURE CHANGES
Since Say on Pay was adopted in 2011, companies have incorporated many new features to make their proxy statement a communications document for shareholders by including a proxy summary, an executive summary in the CD&A and highlighting good governance practices, just to name a few. While Early Filers generally did not make wholesale changes to their proxy statement in 2016, some companies enhanced their disclosure with additional charts and graphs. Some examples include:
- Deere & Co, which has annual incentive performance goals that can vary depending upon the company’s sales volume, added a graph to explain the performance goals, actual results and how each related to the actual sales volume achieved;
- Jabil Circuit, Jacobs Engineering Group and TE Connectivity added a list of corporate governance best practices (i.e., “what we do and what we do not do”);
- Starbucks added a picture describing their shareholder outreach process and topics discussed with shareholders.
We would expect that companies will have more significant changes to the proxy statement as more rules under Dodd-Frank (e.g., pay ratio and pay vs. performance) are finalized and implemented.
CONCLUSION
2015 was not as strong of a performance year as 2014. Given weaker 2015 performance, annual incentive payouts declined from 2014 levels resulting in a directional alignment between pay and performance. 2016 is already shaping up to be an interesting year given recent declines in stock price, currency fluctuations and overall uncertainty given the U.S. Presidential election. Many companies will be making their annual equity grants at depressed stock prices, so we may potentially see a year over year decline in LTI grant values particularly for those companies that grant awards based on a fixed number of shares. From an executive compensation perspective, we expect that the SEC will come out with final rules for the clawback, hedging and pay vs. performance in October 2016 which could have an impact on 2017 and 2018 disclosure.
We believe Mr. Fink raises an important point on linking incentives to business strategy. A clearly communicated business strategy would help to avoid pitfalls that we see frequently today. These include incentives that are designed primarily to respond to pressure from proxy advisory firms, often driving a “one size – fits all” approach or encouraging short-term thinking.
“We are asking that every CEO lay out for shareholders each year a strategic framework for long-term value creation. Additionally, because boards have a critical role to play in strategic planning, we believe CEOs should explicitly affirm that their boards have reviewed those plans. BlackRock’s corporate governance team, in their engagement with companies, will be looking for this framework and board review.”
Larry Fink, BlackRock CEO
As highlighted by our articles Are You Rewarding Short-Termism? in The Corporate Board and Balancing pay for performance with shareholder alignment in the Ethical Boardroom, it is important that compensation, in particular long-term incentive compensation, links directly to the company’s strategy. We agree that providing shareholders with a voice on compensation programs through Say on Pay has been beneficial, but we have observed a chilling effect on creative compensation programs. Today most public companies are very reluctant to be an outlier on compensation. If we look at CAP’s sample of 100 large market cap companies, 51% use Total Shareholder Return (TSR) and 34% use EPS as metrics in their long-term incentive plans. Are these universal metrics appropriate in almost any situation? We question that premise. Why do so many companies have similar metrics when they have unique business strategies, operate in diverse industries and are positioned at different points in their lifecycle?
The good news is that we have observed modest increases in the use of return metrics, from 41% in 2011 to 47% in 2014 (e.g., return on assets, return on capital and return on equity). In several cases, activist investors have intervened to champion the adoption of return metrics. Traditional institutional investors with concerns over the effectiveness of corporate business strategies have also been vocal in encouraging companies to focus on returns. Both camps frequently push companies to move to adopt balanced metrics that encourage profitability in combination with growth as opposed to growth alone.
The chart below provides a snapshot of how long-term incentive plan metrics have evolved over time. Use of TSR has grown most since 2011, from 36% to 51% and this is after dramatic increases prior to 2011. We believe this is the direct outcome of the influence of proxy advisory firms, who have pushed hard on companies to incorporate relative TSR in their programs. The good news is that since 2011, the number of companies relying on a single metric has declined, with over 1/3 of companies using 3 or more metrics which may indicate they are tailoring plans more to their specific situation.
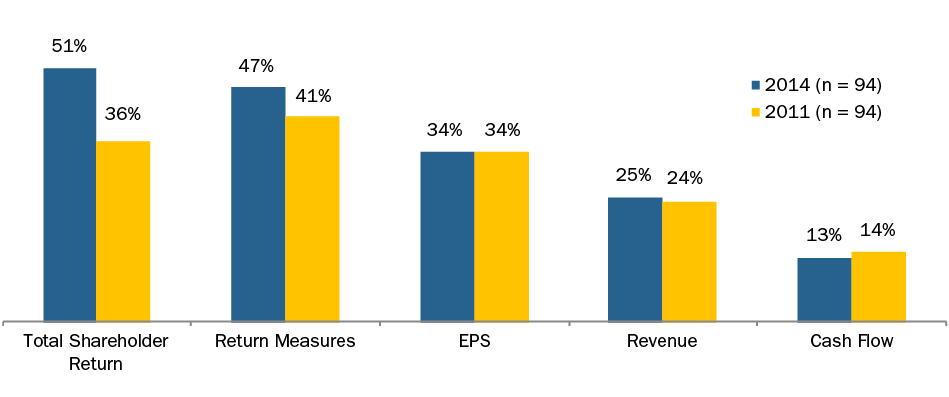
|
# of Metrics |
2011 |
2014 |
|
1 |
33% |
26% |
|
2 |
40% |
37% |
|
3 or More |
27% |
37% |
While EPS and TSR may make sense for many companies, companies should consider various factors when selecting measures, including:
- Is relative TSR the best answer for your company? We see it as an outcome-oriented metric that lacks a clear linkage to strategic priorities and is not well suited to driving behaviors that create shareholder value.
- Does over-reliance on TSR encourage risk-taking behaviors? Companies may make decisions that drive TSR in the short-term (e.g., share buybacks or higher dividends), rather than identifying better uses of capital that can lead to sustained long-term growth.
- Does an EPS metric create an incentive to buy back shares rather than re-investing for growth? Financial experts have mixed views on the utility of share buybacks. The jury is still out.
- Are the current time horizons for TSR performance optimal? Almost all plans measure TSR over 3 years. Why is a 3-year time frame the default for most companies? Since TSR is usually defined as a relative metric, eliminating the need to set goals in advance, should companies be evaluating longer timeframes that align with their business cycles?
- If relative TSR is your company’s metric, where are you in the cycle? Companies and boards need to ask and analyze whether relative TSR goals will pay out for sustained long-term stock price appreciation or for volatility in relative stock price performance. Companies and boards need to understand whether the stock is only recovering from earlier losses that occurred prior to the start of the performance period.
We don’t believe that either EPS or TSR are inherently poor metrics. In many cases, it makes sense for companies to incorporate these metrics into their overall incentive framework. However, it is critical to determine if these metrics are right for a particular company at a -particular time in its life cycle. Keep in mind that long-term incentives are the largest component of pay for many executives. As companies and boards design long-term incentives, they should consider the following questions:
- Does the compensation program support our strategy and do the metrics and goals align with our long-term business plan?
- Can we communicate clearly and succinctly how the program ties to our strategic framework for both shareholders and program participants?
- What behaviors, good or bad, could the design encourage? For example:
- Does it send clear signals throughout the organization on the strategic priorities?
- Is short-term upside emphasized at the expense of long-term sustained value?
- Do we encourage growth at the expense of returns that exceed our cost of capital?
- Does the program encourage excessive or inappropriate risk-taking?
- For metrics other than TSR, will achievement of goals lead to company and shareholder value creation?
- Are there alternative metrics, including strategic metrics (e.g., increase in market share, diversification of revenue, etc.) that might be better indicators of successful execution of the strategy?
Overall, we think Mr. Fink’s commentary on the importance of defining and communicating a company’s strategic framework for value creation serve shareholders well. His comments point to a fundamental principle of compensation design: incentive compensation should be used to reward the company’s success in achieving its strategy and creating long-term value for shareholders. The performance measures used to determine incentive compensation need to track progress on the strategy over the near term and over the long-term. We believe we will see a migration in this direction as long-term incentives evolve, companies continue to dialogue with their shareholders and perhaps as they enhance disclosure around their strategic framework as Mr. Fink suggests.
Partner Bertha Masuda discusses using deferred compensation as a strategy to maximize pay for performance in executive compensation.